As of October 21, 2026.
- The verdict: Up to $600 in cashback is real, but plan on $300 to $400. The last $200 is two separate $100 pieces, and you need both: one for $5,000 in a savings account opened within 15 days, with the balance never dipping until day 120, and one for payments on a National Bank mortgage switched to the new account. And this offer has the sharpest catch in the market: close the account or the card inside 12 months and you pay part of the bonus back.
- Who this is for: New National Bank clients who can move three $100+ automatic deposits into a new chequing account on a fixed schedule, and who will actually keep the account for a full year.
- Your move: Open The Connected package as your first National Bank chequing account by November 3, 2026. Pick Connected over The Total. Then start the deposit schedule right away, because the three deposits land in three separate time windows.
The offer, in one block
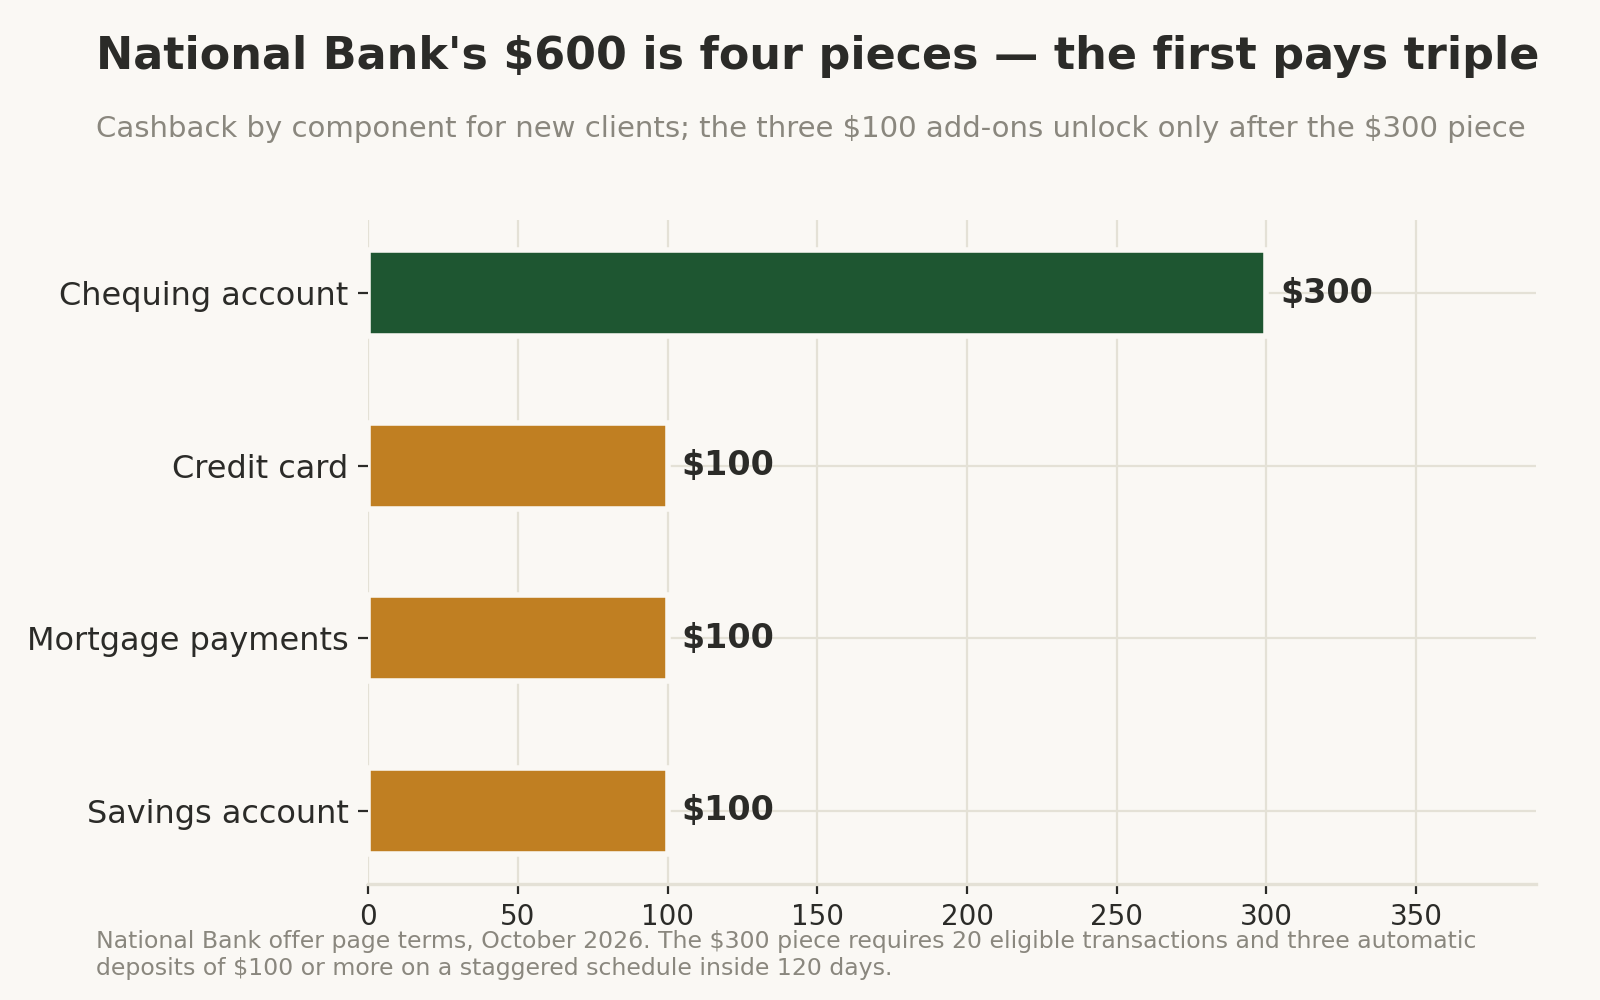
- Bonus: Up to $600 cashback — $300 for the chequing account, plus $100 each for a credit card, a mortgage payment setup, and a savings account.
- Requirements: Open your first National Bank chequing account with The Connected or The Total package during the promotion, then finish each piece inside 120 days of opening. Full breakdown below.
- Expiry: Ends November 3, 2026 (13 days left)
- Payout speed: By the end of the sixth month after you open the chequing account. Open on the November 3 deadline and the outside date is the end of May 2027.
- The catch: Keep the chequing account — and the new credit card, if you get one — for at least 12 months. Close early and you reimburse a portion of the cashback for the product you didn’t keep, based on the time remaining.
Every term below comes from National Bank’s own promotional offer page, which carries the full conditions, and from National Bank’s Fee Guide for Personal Banking Solutions for the package fees. The math is simple addition and subtraction on those published terms.
The four pieces, decoded
| Piece | Value | What it takes | The fine print that matters |
|---|---|---|---|
| Chequing account | $300 | Open your first National Bank chequing account with The Connected or The Total package as primary account holder. Within 120 days of opening: sign up for online banking, complete 20 eligible transactions, and receive 3 eligible automatic deposits of at least $100 each. | The 20 transactions are debit card purchases and bill payments made in online banking or the app. Refunds, monthly fees, and account charges don’t count. The 3 deposits run on a schedule: the first within 60 days of opening, the second between day 60 and day 89, the third between day 90 and day 120. Miss a window and the piece is gone. |
| Credit card | $100 | Within 120 days of opening the chequing account, apply for and get approved for an eligible National Bank Mastercard as primary cardholder, then make at least 20 purchases or cash advances on it. | Eligible cards: Platinum, World, World Elite, mycredit, Allure, MC1, Echo Cashback, and Syncro Mastercard. Interest, annual fees, purchase returns, and Mastercard cheques don’t count toward the 20. You can’t have held a National Bank personal credit card — as primary holder or authorized user — in the past 36 months. Approval isn’t guaranteed, and you must be 18 to get the card. |
| Mortgage payments | $100 | Within 120 days of opening the chequing account, set up pre-authorized, recurring payments for a National Bank mortgage from the new chequing account. | The mortgage has to be a National Bank mortgage. A mortgage at another bank doesn’t count, and taking out a mortgage to chase $100 makes no sense. This piece is only realistic if you already hold a National Bank mortgage. |
| Savings account | $100 | Within 15 days of opening the chequing account, open a High Interest Savings Account, deposit at least $5,000, and keep a minimum balance of $5,000 at all times, without interruption, up to day 120 after opening the chequing account. | The 15-day window is the tightest clock in the offer. One dip below $5,000 breaks the condition. You also can’t have held a National Bank High Interest Savings Account in the past 36 months. |
One gate sits under all four pieces. You only unlock the three $100 add-ons if you first meet every condition for the $300 chequing piece. And you must keep the package in place for at least 120 days after opening.
Eligible deposits for the $300 piece are defined by Payments Canada transaction codes. Payroll, pensions, the Canada Child Benefit, CPP, OAS, and EI all qualify. A transfer from your own account at another bank is not on the list.
The honest math: $300 to $400 is the realistic range
$300 is the piece almost any eligible new client can collect. You need an automatic deposit you can reroute, and you need it to land three times, once in each window.
$400 adds the credit card piece. That needs an approval, no National Bank card in the past 36 months, and 20 purchases. Most applicants who clear the 36-month rule can do this one.
$500 adds the savings piece. You have to open the savings account within 15 days of the chequing account, deposit at least $5,000, and keep the balance at or above $5,000, without interruption, until day 120 counted from the day the chequing account opened.
$600 needs all of the above plus a National Bank mortgage with payments switched to the new account. If you don’t already have that mortgage, treat $600 as out of reach.
Compare the shape with the other big-bank stacks on the bank bonus tracker — the TD $750 decoder and the BMO $900 decoder follow the same pattern of a reachable base and add-ons that thin out fast.
The fee math
The Connected package costs $15.95 a month. The fee is waived if you keep a minimum daily balance of $4,500 in the account. The Total package costs $28.95 a month, waived at a $6,000 minimum daily balance.
- Connected, fee paid for 12 months: $15.95 × 12 = $191.40. Your $300 becomes $108.60. Your $400 becomes $208.60. The full $600 becomes $408.60.
- Connected, fee waived: Keep $4,500 in the account every day and you keep the full bonus. The cost is the interest that $4,500 could earn elsewhere.
- Total, fee paid for 12 months: $28.95 × 12 = $347.40. That alone wipes out the $300 base piece. Pick Total only if you’ll use its extras, such as branch transactions included and a larger credit card annual-fee cashback at enrolment.
Two discounts can soften the Connected fee. Holders of an eligible Platinum, World, or World Elite Mastercard get $5 a month off, and clients aged 60 and over get $5 a month off. Clients aged 24 and under get the Connected fee waived outright. Connected also carries a one-time cashback of up to $30 on an eligible card’s annual fee at enrolment, and Total up to $150. Card annual fees themselves vary by card and sit outside the math above.
If the savings piece puts $5,000 in a National Bank High Interest Savings Account, check what that balance earns against the current field in the promo-rate leaderboard before you lock it in until day 120.
Fit check
Get it if:
- You haven’t held a National Bank chequing account — or most National Bank credit products and lines of credit listed in the terms — in the past 36 months.
- You can reroute a payroll or government deposit of $100 or more, and it will land once in each of the three windows.
- You can hold $4,500 in chequing to waive the fee, or you’ve done the fee math above and still come out ahead.
- You’ll keep the account for a full 12 months anyway.
- You already have a National Bank mortgage, or $5,000 to park, and can reach for the extra pieces.
Skip it if:
- You’ve banked with National Bank in the past 36 months. The lookback covers chequing accounts, several savings and credit products, and personal lines of credit.
- Your deposit can’t hit the schedule. One deposit in the wrong window fails the $300 piece, and the add-ons sit on top of it.
- You’d pay the Total fee for a year. At $347.40, it eats the base bonus whole.
- You plan to close the account as soon as the cashback lands. That’s exactly what the reimbursement clause targets.
- You’re an employee of National Bank or CWB, or an employee’s spouse. The terms exclude you.
The traps
- The reimbursement clause. Keep the new chequing account, and the new credit card if you got one, for at least 12 months from the day the chequing account opened. Close early and you reimburse a portion of the cashback for the product you didn’t maintain, corresponding to the period remaining. The terms don’t publish a formula beyond that, so treat any early close as money owed back.
- The deposit windows. Three deposits of $100 or more sounds easy. The schedule is the trap: one in the first 60 days, one between day 60 and day 89, one between day 90 and day 120. Two deposits in month one and none in month three earns nothing.
- The 15-day savings clock. The savings account must be opened within 15 days of the chequing account, not within 120 days like everything else. Decide on this piece before you open the chequing account.
- The $5,000 can’t dip. The savings balance must stay at or above $5,000 at all times, without interruption, through day 120.
- The 36-month lookbacks stack. One lookback covers past chequing and credit products. A second one covers past National Bank credit cards, including as an authorized user. A third covers a past High Interest Savings Account. Failing any one of them kills only its piece — except the first, which kills everything, because the $300 piece gates the rest.
- Good standing is required. The account must stay in good standing until the cashback is paid. An overdrawn or misused account loses the bonus.
- One cashback only. You may receive only one cashback for this chequing account, and the offer can’t be combined with another National Bank cashback promotion on chequing accounts or banking packages.
The Club take
- Who wins: A true newcomer to National Bank with a reroutable deposit, $4,500 to hold in chequing, and a National Bank mortgage or $5,000 to park. That reader collects $500 to $600 and pays no monthly fee doing it.
- Who should skip: Anyone who held National Bank products in the past 36 months, anyone whose deposit timing is shaky, and anyone who’d close the account inside a year.
- The catch: The headline is $600. The realistic number is $300 to $400, paid by the end of month six, and it’s a loan until month twelve. Close early and part of it goes back.
FAQ
When do you get the money?
By the end of the sixth month after you open the chequing account, deposited into that account. Open on November 3, 2026 and the outside date is the end of May 2027. All pieces pay on that same schedule.
What happens if you close the account early?
You reimburse a portion of the cashback for the product you didn’t keep, corresponding to the period remaining in the 12 months. The same rule covers the new credit card. The terms state the rule but don’t publish an exact formula.
Can existing National Bank clients get this?
Only in a narrow case. This must be your first National Bank chequing account under the offer, and you must not have held a listed National Bank chequing, savings, or credit product — or had a High Interest Savings Account — in the past 36 months. A National Bank mortgage on its own isn’t on that exclusion list, which is why an existing mortgage client switching their chequing can still qualify. You must also be at least 14 years old to open the account.
Does a transfer from another bank count as one of the three deposits?
No. The deposits must be eligible automatic deposits under Payments Canada codes — payroll, pensions, and government benefits such as the Canada Child Benefit, CPP, OAS, and EI. Your own transfers aren’t listed.
Connected or Total: which package should you pick?
Connected, for almost everyone chasing this bonus. At $15.95 a month, waived at a $4,500 daily balance, it costs $156 less over 12 months than Total at $28.95, waived at $6,000. Both packages qualify for the same $600.
Is the offer available in Quebec?
The terms on National Bank’s offer page list no provincial exclusion. Read the full conditions on that page before you open the account, since the promotion can be modified or withdrawn without prior notice.