The verdict
TD has relaunched its big chequing bonus — the page now runs a new round ending November 2, 2026 (the old round’s October 1 deadline is gone from the live page). Get up to $750 in value: a $500 cash bonus for opening an eligible chequing account and completing 2 of 3 qualifying actions, an extra $150 if you bundle in a new savings account plus a new TD credit card, and a 4% bonus interest rate for 90 days on new savings balances up to $1,000,000 (about $100 on a $10,000 balance). Open by November 2, 2026, complete the qualifying actions by January 4, 2027. If you’ve been waiting to switch banks, this is the signal.
Who this is for
Anyone opening a new TD chequing account who can route payroll direct deposit or set up pre-authorized debits — and who is willing to add a TD savings account and credit card to unlock the full $750. Not for existing TD chequing customers — the offer is framed around a new eligible chequing account, and TD’s prior chequing offers explicitly excluded anyone already holding a TD chequing account; read the full legal terms on TD’s page to confirm you qualify.
Your move
Open a TD Unlimited Chequing Account ($17.95/month, waived at a $4,000 minimum daily balance) or TD All-Inclusive Banking Plan ($30.95/month, waived at a $6,000 minimum daily balance) by November 2, 2026, then complete two of the three qualifying actions — recurring direct deposit, recurring pre-authorized debit, online bill payment — by January 4, 2027.
On this page
- The round is new — here’s what changed
- Breaking down the $750
- The requirement chain, with exact dates
- The fine print: fees and trade-offs
- Who should skip this
- Your move: step by step
The round is new — here’s what changed
Our October alert on TD’s up-to-$750 offer expired October 1 and was pulled from the site — the old round’s October 1 deadline no longer appears on TD’s page. TD now advertises a new round with the same headline structure — up to $750 in value — but with new deadlines. Everything below is based on TD’s current page as of October 3, 2026; the two prior-round notes are labeled as context, not current terms.
The headline deadlines for this round:
| Deadline | What it applies to |
|---|---|
| November 2, 2026 | Open the new eligible chequing account |
| January 4, 2027 | Complete 2 of 3 qualifying actions |
| Within 30 days of chequing account opening | Open new savings account; apply and be approved for new TD credit card |
| Within 30 days of savings account opening | Set up pre-authorized transfer service or Simply Save |
Breaking down the $750
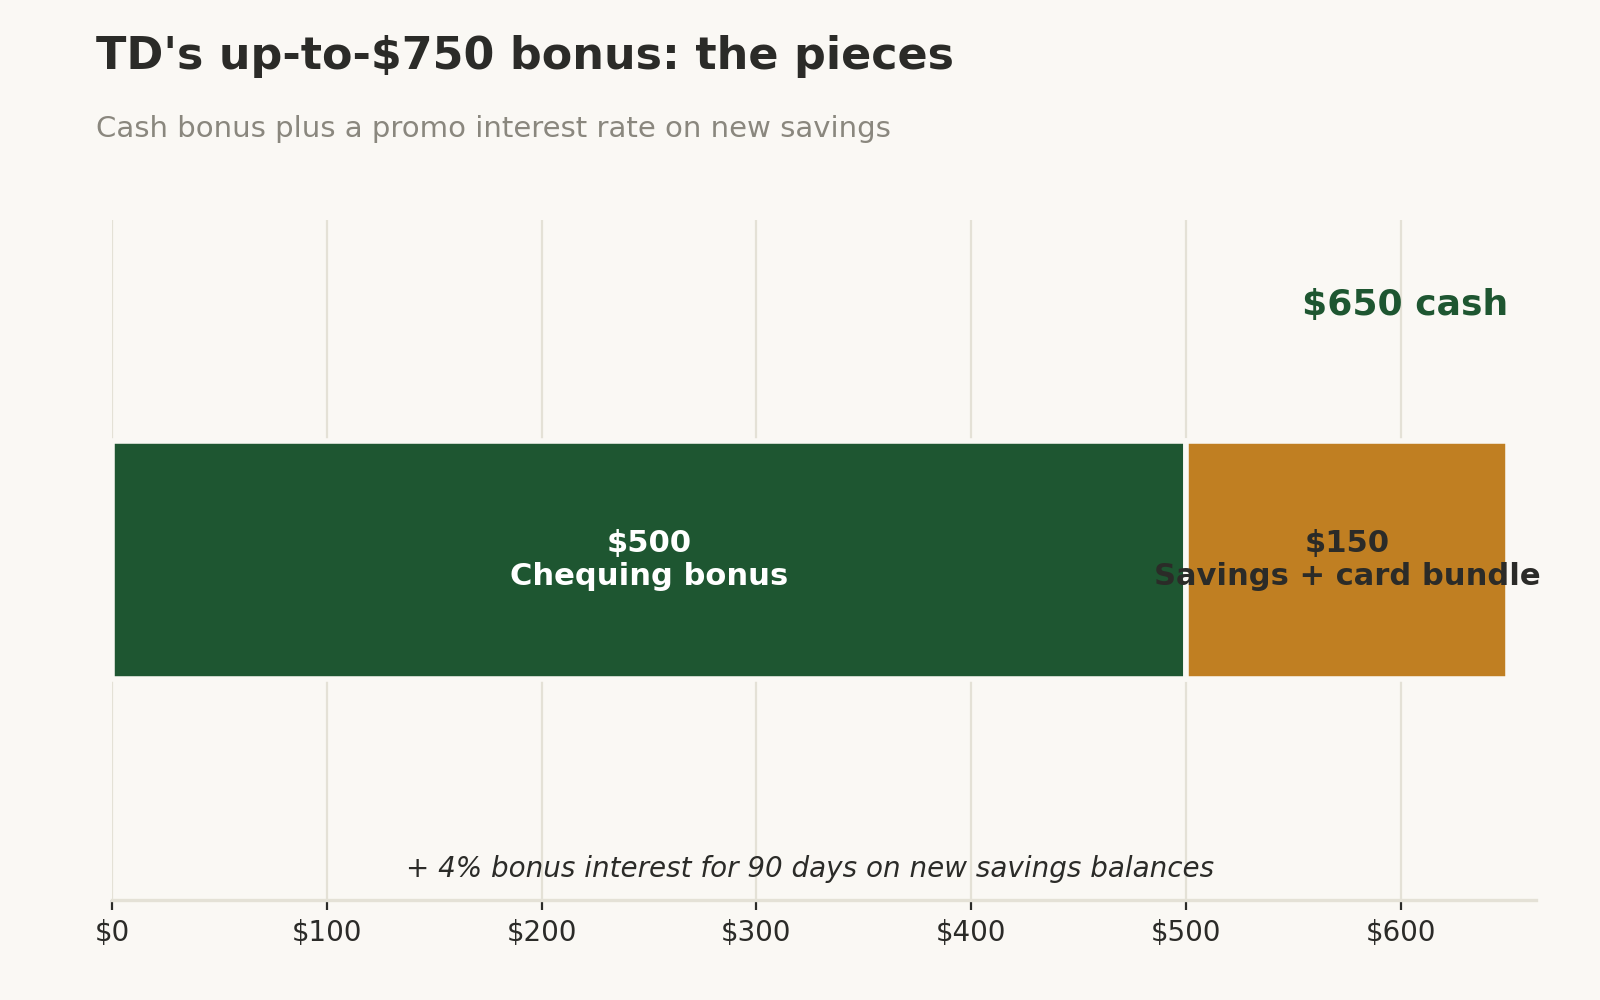
The “$750 in value” is three separate pieces. They stack:
| Piece | Value | What you do |
|---|---|---|
| Chequing bonus | $500 | Open a new TD Unlimited Chequing Account or TD All-Inclusive Banking Plan by November 2, 2026, and complete 2 of 3 qualifying actions by January 4, 2027 |
| Bundle bonus | $150 | Open a new eligible savings account within 30 days of the chequing account and set up a pre-authorized transfer service or Simply Save within 30 days of opening the savings account — and apply and be approved for a new eligible TD credit card within 30 days of opening the chequing account |
| Bonus interest | 4% for 90 days (about $100 on a $10,000 balance) | Open and deposit into a new eligible savings account; earn a 4% bonus interest rate on top of the posted rate, on balances up to $1,000,000 |
On the interest piece: TD’s example says you could earn 4.45% with a TD ePremium Savings Account when you deposit more than $10,000 — that’s the 4% bonus stacked on the ~0.45% posted rate (TD’s own savings page shows the ePremium posted rate up to 0.45% on balances of $10,000 or more). The more you park, the more the interest component is worth — and unlike the cash bonuses — which pay fixed dollar amounts — the interest scales with your balance, up to the $1,000,000 ceiling on eligible balances. At 4% for 90 days, a $10,000 balance earns about $100 in bonus interest — the piece that completes the advertised $750 next to the $500 and $150 — and a $100,000 balance earns roughly $990 in bonus interest alone, more than the $500 + $150 cash pieces combined; at the $1,000,000 ceiling that’s roughly $9,900. For large balances, the interest is where the real money is.
The requirement chain, with exact dates
This is where people slip. The conditions chain off each other — miss one link and the bonus shrinks. Here’s the full chain:
- Open the chequing account by November 2, 2026. Eligible accounts: TD Unlimited Chequing Account or TD All-Inclusive Banking Plan. This starts the clock on everything else.
- Complete 2 of 3 qualifying actions by January 4, 2027:
- Receive a recurring direct deposit
- Set up a recurring pre-authorized debit payment
- Make an online bill payment
- For the extra $150 — two tracks, both inside 30 days:
- Savings track: open the new eligible savings account within 30 days of opening the chequing account, then set up a pre-authorized transfer service or Simply Save within 30 days of opening the savings account.
- Credit card track: apply and be approved for a new eligible TD credit card within 30 days of opening the chequing account.
The calendar math: if you open the chequing account on November 2 (the last possible day), your qualifying actions must be done by January 4 — nine weeks to get a direct deposit flowing or set up debits. Open earlier and you have more runway, but the credit card approval is the step with the least margin for error.
The fine print: fees and trade-offs
- Monthly account fees: TD Unlimited Chequing is $17.95/month, or $0 if you maintain a daily balance of $4,000 or more. TD All-Inclusive Banking Plan is $30.95/month, or $0 if you maintain a daily balance of $6,000 or more.
- Credit card fee rebates: Unlimited includes a first-year TD credit card annual fee rebate up to $139; All-Inclusive includes an annual rebate up to $139.
- Unlimited transactions are included on both accounts, including free Interac e-Transfers.
- Bonus payout timing: the current round’s offer summary doesn’t state when the $500 or $150 are paid after conditions are met. For context, TD’s prior chequing offers deposited the cash bonus within 12 weeks after all conditions were met (per TD’s own FAQ for the round that ended June 26, 2026) — but that timing is not confirmed for this round, so don’t plan around it until you read the current legal terms.
- Who’s eligible: the current offer summary doesn’t restate the new-customer / prior-account-holder exclusions. TD’s prior round explicitly excluded customers who already held a TD chequing account (other than a U.S. Dollar Account) — the cash offer was “only available to new TD All-Inclusive Banking Plan or TD Unlimited Chequing Account customers.” Assume the same applies until you confirm otherwise in this round’s legal terms.
Who should skip this
- Existing TD chequing customers — TD’s prior rounds excluded anyone already holding a TD chequing account; confirm in the current legal terms before assuming you qualify.
- Anyone who can’t move a direct deposit or set up debits — two of the three qualifying actions require recurring flows, not one-off transfers.
- Anyone allergic to minimum balances — $4,000 or $6,000 sitting idle to dodge monthly fees is a real opportunity cost; if you’d pay the monthly fee, that eats into the bonus.
- Anyone who needs the credit card fast — the 30-day apply-and-approve window is the tightest link in the chain; if approval drags, the $150 bundle disappears.
Your move: step by step
- Read TD’s official offer terms — especially the legal fine print at the bottom of the page — and confirm you’re eligible before opening anything.
- Open the chequing account by November 2, 2026. Sooner is better: the 30-day windows are anchored to your chequing account’s opening date — they don’t shrink. What shrinks is your runway to the January 4, 2027 deadline for completing the qualifying actions.
- Within 30 days of opening the chequing account, open the new savings account and apply for the credit card; then set up your transfer service or Simply Save within 30 days of opening the savings account.
- Set up your direct deposit and/or pre-authorized debits immediately — payroll changes can take a pay cycle or two, and the hard deadline is January 4, 2027.