As of October 20, 2026.
Five banks are running promo rates on savings right now. The headline rates say BMO wins. The dollars say otherwise. This board ranks all five by what you actually earn on $10,000 and $50,000 over each promo window — and shows the rate your money falls to the day the promo ends. For cash bonuses instead of rates, see the Club’s bank bonus tracker.
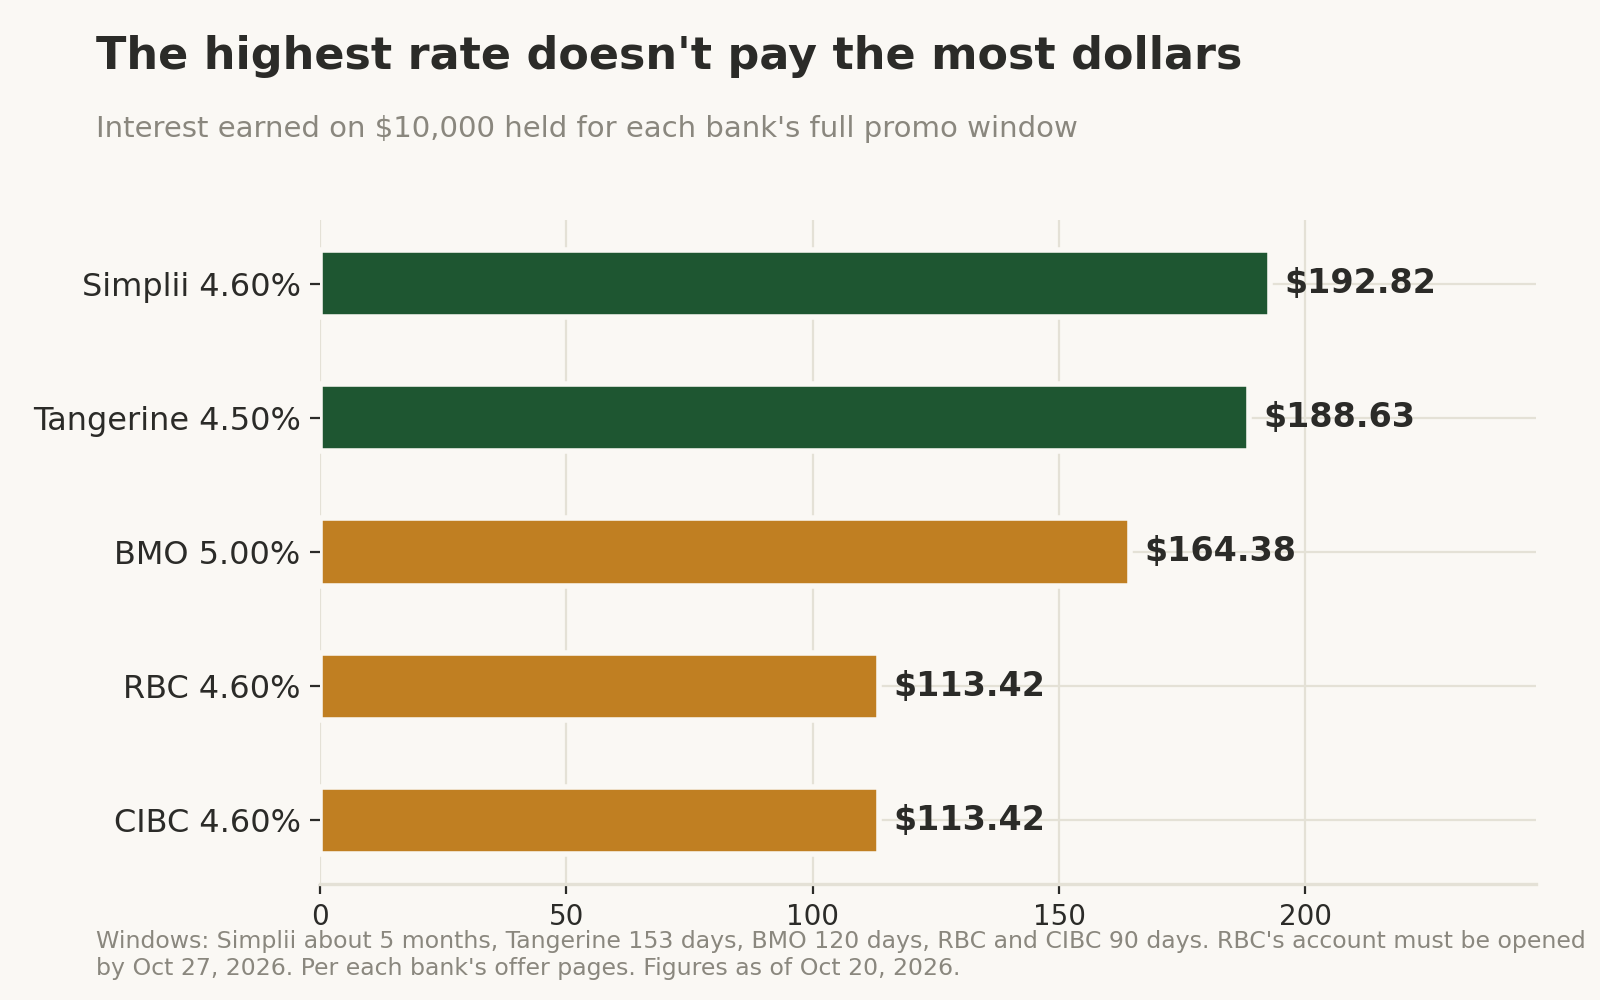
The verdict: $192.82 on $10,000 — Simplii’s 4.60% over ~5 months pays more total dollars than BMO’s headline 5.00% over 120 days ($164.38), because the window is longer. On $50,000 it’s $964.11 versus $821.92. Every offer here falls off a cliff when the promo ends — the best post-promo rate on this board at these balances is 0.55%.
Who this is for: You have $10,000–$50,000 sitting in a low-rate account and you qualify as a new client at one of these banks.
Your move: Pick by dollars and deadline, not by headline rate. If RBC is your pick, open it this week — Ends October 27, 2026 — 7 days left.
The leaderboard
| Bank | Promo rate | Window | $ earned on $10,000 | $ earned on $50,000 | Rate after the promo |
|---|---|---|---|---|---|
| Simplii HISA | 4.60% | ~5 months (~153 days*) | $192.82 | $964.11 | 0.30% at these balances (tiered) |
| Tangerine Savings | 4.50% | 153 days (5 months) | $188.63 | $943.15 | Tangerine’s posted rate |
| BMO Savings Amplifier | 5.00% | 120 days | $164.38 | $821.92 | 0.45% |
| RBC High Interest eSavings | 4.60% | 90 days (3 months) | $113.42 | $567.12 | 0.55% |
| CIBC eAdvantage Savings | 4.60% | 90 days | $113.42 | $567.12 | Tiered regular rates |
Math: simple interest, principal × rate × days ÷ 365, balance held for the full window. Day counts: BMO 120 days, RBC 90 days, CIBC 90 days, Tangerine 153 days. *Simplii publishes “5 months” with no exact day count on its pages, so the Simplii dollars above assume ~153 days — the same span Tangerine publishes for its 5-month offer.
Ranked by dollars earned over the promo window on the banks’ own published terms.
The cliff
The promo rate is rented, not owned. Park $10,000 and leave it after the window closes, and a full year earns you $55 at RBC (0.55%), $45 at BMO (0.45%) and $30 at Simplii (0.30% at these balances). CIBC falls back to tiered regular rates and Tangerine to its posted rate — neither bank publishes a current value in readable form on its own pages, so no dollar figure is shown for them here. During the promo, that same $10,000 earns $113 to $193 in 3 to 5 months. The move is to calendar the end date and move the money when the rate drops — the where-to-park-cash guide covers your options when a promo runs out.
1. Simplii Financial — High Interest Savings Account
Rate: 4.60% on eligible deposits up to $200,000 for 5 months. Simplii does not publish an exact day count for the 5 months. The dollars in the table assume ~153 days.
Requirements: New Simplii clients. Already a client? You qualify only if you open the savings account within your first 60 days with Simplii. No minimum balance.
Expiry: Ends October 31, 2026 — 11 days left
Payout speed: Interest calculated daily, paid into your account monthly.
The catch: The $200,000 cap is the lowest on this board. When the promo ends, the rate drops to tiered regular rates starting at 0.30% — 0.30% applies at both $10,000 and $50,000 balances, and the top tier of 1.00% only starts above $1,000,000. More detail in the Club’s Simplii 4.60% post.
- Get this if you: You’re new to Simplii and want the most total dollars from a single promo window.
- Skip it if you: You’re past your first 60 days as a Simplii client, or you’re parking more than $200,000.
2. Tangerine — Savings Account
Rate: 4.50% for 153 days (5 months) on non-registered savings, on deposits up to $1,000,000.
Requirements: New Tangerine clients only. Your Client Number must be created between July 28, 2026 and November 30, 2026, and you must open the account as primary account holder within 60 days of that date, per Tangerine’s offer terms. The 153-day clock starts the day your first eligible savings account opens.
Expiry: Ends November 30, 2026 — 41 days left (the last day to create a new Tangerine Client Number and qualify; your 153 days run from your first account opening)
Payout speed: Interest calculated daily, paid monthly, per Tangerine’s offer terms.
The catch: Open a registered savings account first and the same 153-day clock governs your non-registered account too — Tangerine’s own example shows a later-opened account only gets whatever time is left. After the promo, the account falls to Tangerine’s posted rate. Tangerine does not publish the current posted-rate value in readable form on its offer or rates pages, so no figure is shown here.
- Get this if you: You’re brand-new to Tangerine and want a long window with no chequing account required.
- Skip it if you: You’re an existing Tangerine client — this rate is new clients only.
3. BMO — Savings Amplifier Account
Rate: 5.00% for up to 120 days from the account opening date, on balances up to $1,000,000. The highest rate on this board — and only the third-best payout, because 120 days is a short window.
Requirements: This is a bundle, not a standalone savings offer. To qualify, BMO requires you to open a new Primary Chequing Account (Blue Rewards, Performance, Premium, Practical or Plus plan), open a new Savings Amplifier Account, and make a deposit. BMO frames the promo as an offer for new BMO customers opening a chequing account together with a Savings Amplifier. The account itself has no monthly fee and no minimum deposit, per BMO’s Savings Amplifier page.
Expiry: Ends November 2, 2026 — 13 days left (the open-by date for the qualifying chequing account and Savings Amplifier in BMO’s current offer)
Payout speed: Interest calculated on the daily closing balance, paid monthly, per BMO’s offer terms.
The catch: No BMO chequing account, no 5.00%. After 120 days the account falls to its regular rate of 0.45%. The rate also ties into BMO’s $900 bundle: deposit $10,000 or more within 30 days, hold it through the 120-day promo window and then for 90 more days, and you add a $150 cash bonus on top — the full steps are in the Club’s BMO $900 bundle post.
- Get this if you: You’re opening a BMO chequing account anyway — the 5.00% is the bundle’s built-in kicker, and the chequing cash is the bigger prize.
- Skip it if you: You only want a savings account. Two other offers on this board pay more total dollars with no chequing requirement.
4. RBC — High Interest eSavings
Rate: 4.60% for 3 months on balances up to $1,000,000. RBC builds it as a 4.05% bonus rate on top of its 0.55% regular rate, and RBC defines the 3 months as exactly 90 days.
Requirements: Your first RBC High Interest eSavings account. RBC’s rule is strict: you must never have been the primary owner of one before June 12, 2026. No minimum balance and no monthly fee.
Expiry: Ends October 27, 2026 — 7 days left (RBC’s cutoff is 3:00 PM EST that day)
Payout speed: Interest calculated daily, paid monthly.
The catch: The shortest window on the board, tied with CIBC — 90 days turns 4.60% into $113.42 on $10,000. The consolation: RBC’s regular rate of 0.55% is the best rate to land on after a promo ends on this board.
- Get this if you: You’ve never held this RBC account and you can open it before the October 27 cutoff.
- Skip it if you: You’ve been the primary owner of an RBC High Interest eSavings account before — you don’t qualify, no matter how long ago you closed it.
5. CIBC — eAdvantage Savings Account
Rate: 4.60% for 3 months on your first eAdvantage account. The structure is a build, not a flat rate: CIBC’s offer terms set a special rate on balances up to $1,000,000 for 90 days, made up of the regular rate for your balance tier plus a bonus rate. If the regular rate moves mid-window, the bonus adjusts so the special rate stays the same.
Requirements: Your first CIBC eAdvantage Savings Account — if you’ve held one before, you don’t qualify. For a joint account, at least one holder must be a first-timer. You must make a deposit during the 90-day window to accept the offer.
Expiry: No end date announced
Payout speed: Regular and bonus interest are each calculated daily and paid monthly.
The catch: Same 90-day math as RBC — $113.42 on $10,000 — but a lower landing spot: after the window, you earn CIBC’s tiered regular rates, which rise with your balance tier. CIBC’s pages render the current tier values via script, so they can’t be quoted here — check CIBC’s rates page for today’s values. The account also charges $5.00 per transaction — debit purchases, withdrawals, bill payments and e-Transfers all count — so treat it as a parking spot, not a spending account. If you’d rather have cash than a rate at CIBC, see the Club’s CIBC Smart bonus post.
- Get this if you: You’re a first-time eAdvantage holder with no deadline pressure — this is the only offer here with no announced end date.
- Skip it if you: You’ll transact from the account. At $5 per transaction, a few moves erase the interest.
FAQ
Which promo pays the most?
Simplii, in total dollars: $192.82 on $10,000 and $964.11 on $50,000 over its ~5-month window. BMO has the highest rate but a shorter window, so it pays less overall — $164.38 and $821.92.
Is BMO’s 5.00% really the best rate?
It’s the best rate and the third-best payout. Rate × time is what you spend. 5.00% for 120 days earns less than 4.60% or 4.50% held for ~153 days. BMO pulls ahead only if you also collect the chequing-side cash in its $900 bundle.
What happens when the promo ends?
Your balance drops to the bank’s regular rate automatically — 0.55% at RBC, 0.45% at BMO, and 0.30% at Simplii at the $10,000 and $50,000 balances used here. Nothing locks you in. The standard play is to move the money to the next promo or a higher everyday rate before the window closes.
Can I stack a promo rate with a bank bonus?
Sometimes — it depends on the bank’s own terms. At BMO, yes: the 5.00% is Step 2 of the $900 bundle. At CIBC, the eAdvantage rate offer cannot be combined with any other offer on the same account. At Tangerine, the rate offer can’t be combined with other promotional savings rate offers. Read each offer’s terms before you count on both.
Do I pay tax on the interest?
Yes, in a non-registered account. Savings interest is taxed as income in Canada — it forms part of your total income and is reported on line 12100, usually on a T5 slip from your bank; you may not receive a T5 for amounts under $50, but the income is still reportable, per the CRA. Interest inside a TFSA savings account is not taxed — but none of the headline rates above are TFSA rates, and Tangerine’s registered-account promo is a separate 5.00% offer with its own terms.
Can I do more than one of these?
Each offer is first-account or new-client only at its own bank, and nothing in the terms above stops you from holding accounts at different banks. Sequence them: when one window closes, the next bank’s promo is your landing spot.
The Club’s take
Who wins: Simplii on dollars — $192.82 on $10,000 — if you’re a new client who opens by October 31. Tangerine is a close second with the longest confirmed window (153 days) and no chequing strings. BMO wins only as part of its $900 bundle.
Who should skip: Anyone who has already held the specific account at that bank — every offer here is first-account or new-client only — and anyone who will leave the money sitting after the promo ends. At 0.30%–0.55%, a forgotten balance gives back the promo’s edge within a couple of years.
The catch: The headline rate is the smallest part of these offers. Window length decides the dollars, the post-promo rate decides what happens next, and two deadlines land within days: RBC on October 27 and Simplii on October 31.