As of October 20, 2026.
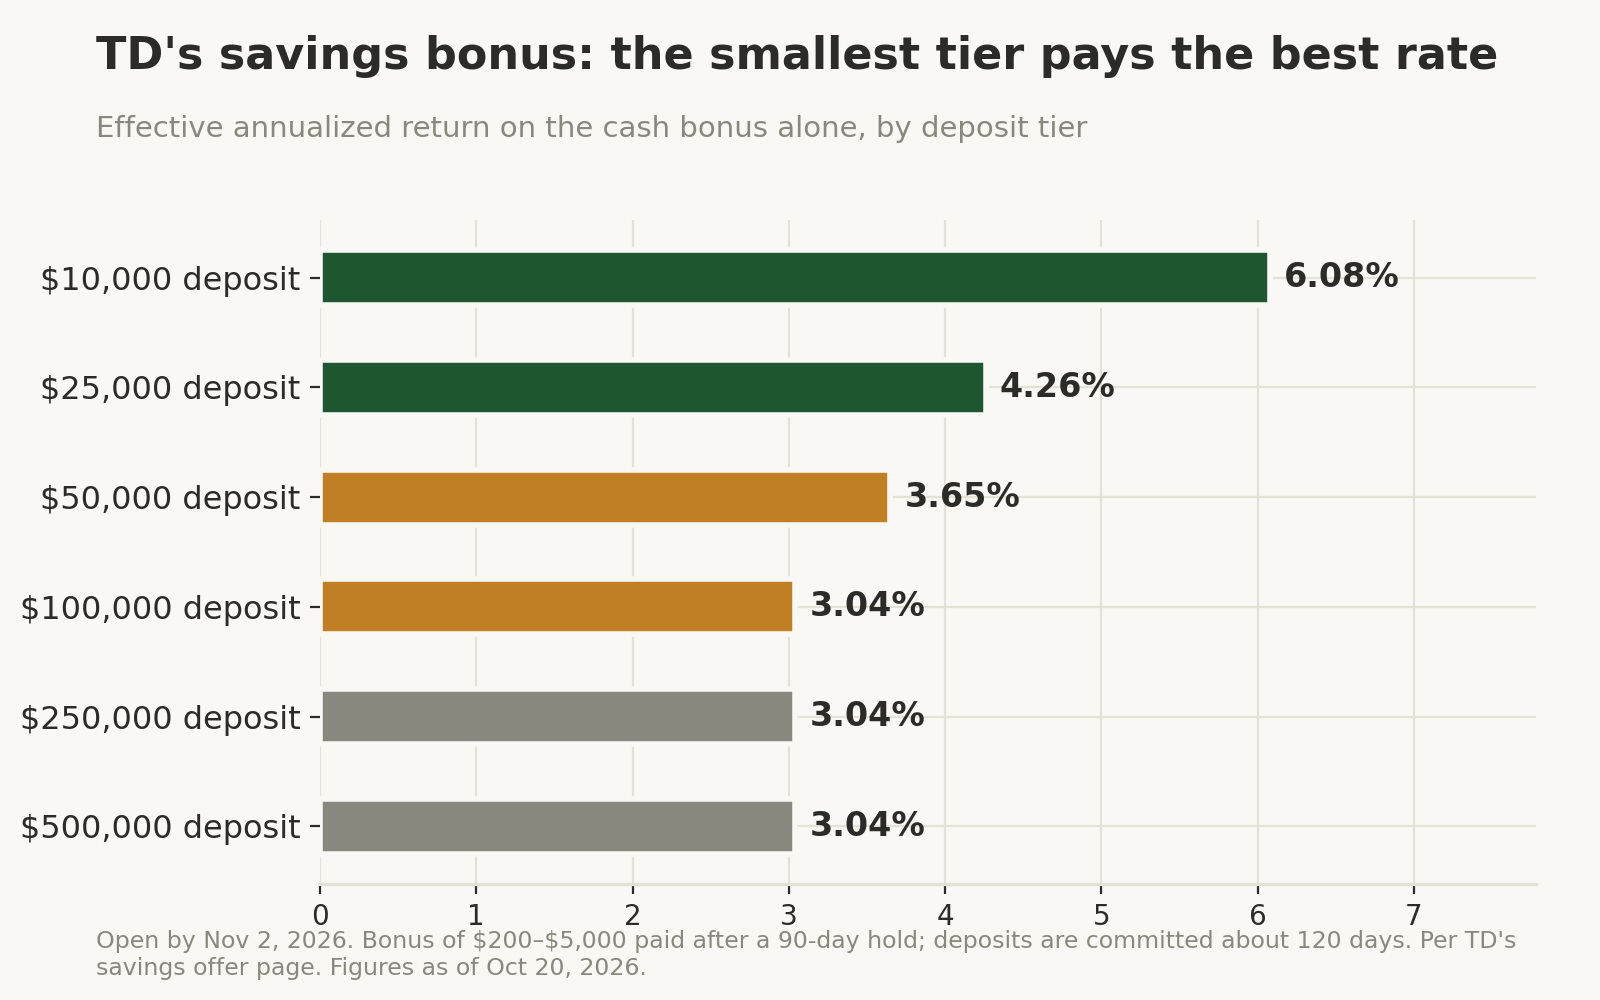
The verdict: $200 for parking $10,000 is the strongest tier in this offer — 2.00% of your deposit, a 6.08% effective annualized return on the bonus alone over the ~120-day commitment. The $5,000 headline takes a $500,000 deposit and pays 1.00% (TD’s savings offer page).
Who this is for: You have $10,000 or more sitting at another bank, you did not hold a TD savings account on June 3, 2026, and you can leave the money untouched for about four months.
Your move: Open one of the three eligible accounts by November 2, 2026, deposit at the bottom of a tier — exactly $10,000 is the sweet spot — and do not touch it during the 90-day hold.
The six tiers, decoded
TD pays the bonus on money you bring in from another financial institution, not on money you move from an existing TD account (TD’s savings offer page). The table below prices every tier at its minimum deposit, because that is where each bonus is worth the most.
| Deposit range | Cash bonus | Bonus % at tier minimum | Effective annualized (bonus only, 120 days) | Interest over the 90-day hold (ePremium, 0.45%) | Bonus + interest |
|---|---|---|---|---|---|
| $10,000–$24,999.99 | $200 | 2.00% | 6.08% | $11.10 | $211.10 |
| $25,000–$49,999.99 | $350 | 1.40% | 4.26% | $27.74 | $377.74 |
| $50,000–$99,999.99 | $600 | 1.20% | 3.65% | $55.48 | $655.48 |
| $100,000–$249,999.99 | $1,000 | 1.00% | 3.04% | $110.96 | $1,110.96 |
| $250,000–$499,999.99 | $2,500 | 1.00% | 3.04% | $277.40 | $2,777.40 |
| $500,000+ | $5,000 | 1.00% | 3.04% | $554.79 | $5,554.79 |
Deposit ranges and cash bonuses are TD’s published tiers (TD’s savings offer page). The math is The Club’s, and you can redo it:
- Bonus % = bonus ÷ deposit at the tier minimum. Example: $200 ÷ $10,000 = 2.00%.
- Effective annualized (bonus only) = bonus % × 365 ÷ 120, where 120 days is the full commitment — 30 days to get the deposit in, plus the 90-day hold. Example: 2.00% × 365 ÷ 120 = 6.08%.
- Interest over the hold = deposit × 0.45% × 90 ÷ 365, simple interest at the TD ePremium Savings rate of 0.45% on balances of $10,000 or more (TD’s savings offer page). Example: $10,000 × 0.45% × 90 ÷ 365 = $11.10.
Two things the headline hides:
- Bigger deposits do not pay a better rate. The percentage falls as the tiers rise — 2.00% at $10,000, 1.00% at $100,000 and every tier above it. You get more dollars at the top tiers. You do not get a better deal.
- Where you land inside a tier matters as much as the tier. Deposit $24,999.99 and you still get $200 — that is 0.80%, a 2.43% effective annualized return, not 6.08%. Deposit at the bottom of a tier, or push to the bottom of the next one. Anything in between dilutes your bonus.
Methodology: tiers decoded by effective annualized return over the 120-day commitment, using TD’s own published terms.
The deadline chain
Four dates run this offer. Miss one and the bonus is gone.
- Open by November 2, 2026. Open a new TD ePremium Savings, TD Growth Savings, or TD Every Day Savings Account by that date (TD’s savings offer page). Ends November 2, 2026 — 13 days left.
- Deposit within 30 days of opening. Move $10,000 or more directly from another financial institution into the new account (TD’s savings offer page). Open on the last day, November 2, and your deposit deadline is December 2, 2026.
- Hold for 90 days, starting on day 31. The balance has to stay for 90 days starting from the 31st day after opening (TD’s savings offer page). Open on November 2 and the hold runs to about March 2, 2027 — 120 days after opening.
- Get paid within 12 weeks after the conditions are met. TD deposits the cash into your new savings account within 12 weeks after all conditions are met, and the account has to be open and in good standing at payout (TD’s savings offer page). Open on the last day, meet everything, and the cash could land as late as about May 25, 2027. Your deposit is free to move after the hold ends. The bonus can trail it by up to three more months.
Pick your account: the three eligible options
The bonus table is the same whichever account you choose. The account decides what your money earns while it sits there — and that gap is bigger than you would expect.
TD ePremium Savings Account
The simple option. You get one flat rate and no tier homework. TD lists up to 0.45% on balances of $10,000 or more, unlimited free online transfers to your other TD deposit accounts, and a $0 monthly fee (TD’s ePremium Savings Account page).
- Bonus $ potential: Up to $5,000, from the same six tiers above (TD’s savings offer page)
- Interest rate: 0.45% on total balances of $10,000 to $1,000,000; 0.000% below $10,000 (TD’s About Our Interest Calculations (PDF))
- Requirements: Open by November 2, 2026; deposit $10,000+ from another financial institution within 30 days; hold 90 days from day 31; no TD savings account held as of June 3, 2026 (TD’s savings offer page)
- Expiry: Ends November 2, 2026 — 13 days left
- Payout speed: Within 12 weeks after all conditions are met, paid into the new savings account (TD’s savings offer page)
- The catch: Drop below $10,000 and the account pays 0.000% interest — and a drop below $10,000 during the hold kills the bonus too. Transactions cost $5.00 each; only the online transfers to your other TD accounts are free (TD’s ePremium Savings Account page)
Get this if you: want the bonus with the least moving parts — one rate, no chequing account or monthly transactions needed to earn it.
Skip it if you: might dip below $10,000 during the hold, or you need to make transactions from the account — each one costs $5.00.
TD Growth Savings Account
The higher-rate option, with strings. TD lists tiered rates up to 1.50% with the Boosted rate, unlimited free transfers to your other TD deposit accounts, and a $0 monthly fee (TD’s savings offer page). The standard posted rates are lower: 0.400% on balances of $10,000 to $99,999.99, 0.550% on $100,000 to $499,999.99, and 0.650% on $500,000 and over (TD’s About Our Interest Calculations (PDF)). The Boosted rate needs an eligible TD chequing account — TD Unlimited Chequing, TD All-Inclusive Banking Plan, or TD Wealth Private Banking Chequing — plus at least 2 of 3 qualifying monthly transactions on that chequing account: a direct deposit, a pre-authorized debit, or an online bill payment (TD’s Growth Savings Account page).
- Bonus $ potential: Up to $5,000, from the same six tiers above (TD’s savings offer page)
- Interest rate: Standard posted — 0.000% below $10,000; 0.400% at $10,000–$99,999.99; 0.550% at $100,000–$499,999.99; 0.650% at $500,000+ (TD’s About Our Interest Calculations (PDF)). Boosted — up to 1.50% if you meet the chequing and monthly transaction conditions (TD’s Growth Savings Account page). TD publishes only the “up to 1.50%” Boosted headline on its account page and in its interest document — no per-tier Boosted rate table — so no tier-by-tier Boosted figures are given here.
- Requirements: Open by November 2, 2026; deposit $10,000+ from another financial institution within 30 days; hold 90 days from day 31; no TD savings account held as of June 3, 2026 (TD’s savings offer page)
- Expiry: Ends November 2, 2026 — 13 days left
- Payout speed: Within 12 weeks after all conditions are met, paid into the new savings account (TD’s savings offer page)
- The catch: The 1.50% headline is the top Boosted rate, not the standard rate. Without the eligible chequing account and the 2-of-3 monthly transactions, you earn the standard posted rate. Transactions on this account cost $5.00 each; transfers to your other TD accounts are free (TD’s Growth Savings Account page)
Get this if you: already have, or were going to open, an eligible TD chequing account and can run 2 of the 3 qualifying transactions every month — at $500,000, the standard 0.650% alone pays $801.37 over the 90-day hold, versus $554.79 at the ePremium rate.
Skip it if you: do not want a TD chequing relationship. At $10,000, the standard Growth rate of 0.400% pays $9.86 over the hold — less than ePremium’s $11.10 — and the Boosted rate never switches on.
TD Every Day Savings Account
The access option, and the wrong home for bonus money. Every dollar earns interest calculated daily, you get 1 transaction per month included, and the monthly fee is $0 (TD’s Every Day Savings Account page). The rate is 0.010% at every balance level (TD’s About Our Interest Calculations (PDF)). On $10,000, that is $0.25 over the entire 90-day hold.
- Bonus $ potential: Up to $5,000, from the same six tiers above (TD’s savings offer page)
- Interest rate: 0.010% on the total balance, at every tier from under $1,000 to $60,000 and over (TD’s About Our Interest Calculations (PDF))
- Requirements: Open by November 2, 2026; deposit $10,000+ from another financial institution within 30 days; hold 90 days from day 31; no TD savings account held as of June 3, 2026 (TD’s savings offer page)
- Expiry: Ends November 2, 2026 — 13 days left
- Payout speed: Within 12 weeks after all conditions are met, paid into the new savings account (TD’s savings offer page)
- The catch: The bonus is identical, but your parked money earns almost nothing — $0.25 on $10,000 over the hold, $12.33 on $500,000. You also get only 1 transaction per month included — additional transactions are $3.00 each (TD’s Every Day Savings Account page)
Get this if you: value monthly access over interest and are only in this for the bonus cash.
Skip it if you: care about the interest at all. Same bonus, same hold, and ePremium pays 45 times the rate on a $10,000 balance.
What your money earns while it’s parked
The bonus does the work in this offer. The interest is a top-up, and the account you pick sets its size. At the tier minimums over the 90-day hold, simple interest (deposit × rate × 90 ÷ 365):
- ePremium at 0.45%: $11.10 on $10,000; $110.96 on $100,000; $554.79 on $500,000 (TD’s About Our Interest Calculations (PDF))
- Growth at standard posted rates: $9.86 on $10,000 at 0.400%; $135.62 on $100,000 at 0.550%; $801.37 on $500,000 at 0.650% (TD’s About Our Interest Calculations (PDF))
- Every Day at 0.010%: $0.25 on $10,000; $2.47 on $100,000; $12.33 on $500,000 (TD’s About Our Interest Calculations (PDF))
Rates can change without notice, per TD’s interest document — the figures above use the rates in that document, dated December 18, 2025, and the account pages read on October 20, 2026 show the same 0.45% ePremium rate and the same up-to-1.50% Growth headline (TD’s About Our Interest Calculations (PDF)).
Stacking this with a chequing bonus? Read TD’s chequing offer, decoded the same way. For every current offer in one table, see the Club’s bank bonus tracker. And before you park cash anywhere for four months, check where to park cash in Canada in 2026.
FAQ
Is the TD $5,000 savings bonus worth it?
At the right deposit, yes. Park exactly $10,000 and the $200 bonus is 2.00% over a ~120-day commitment — a 6.08% effective annualized return on the bonus alone, plus $11.10 of interest at the ePremium rate of 0.45% (TD’s savings offer page). The $5,000 tier pays more cash but a worse rate: 1.00% on $500,000. Deposit at the bottom of a tier, never just under the top of one.
Who qualifies for the TD savings bonus?
You need a new TD ePremium Savings, TD Growth Savings, or TD Every Day Savings Account opened by November 2, 2026, a deposit of $10,000 or more from another financial institution within 30 days, and a 90-day hold starting on day 31. If you held a TD savings account as of June 3, 2026, you do not qualify (TD’s savings offer page).
When do I get paid?
Within 12 weeks after all conditions are met. TD deposits the cash into the new savings account, and the account has to be open and in good standing at payout (TD’s savings offer page). Open on November 2, 2026 and hold to about March 2, 2027, and the bonus could arrive as late as about May 25, 2027.
What if I withdraw during the 90-day hold?
The amount you withdraw is subtracted and your bonus is recalculated on what is left. If the adjustment drops your qualifying funds below $10,000, you are ineligible for the offer (TD’s savings offer page). A partial withdrawal can also knock you down a tier — pull $1 out of a $25,000 deposit and the remaining $24,999 drops you to the $200 tier.
Do transfers from my TD chequing account count?
No. Transfers originating from existing TD accounts do not qualify. The money has to come directly from another financial institution — TD lists Interac e-Transfer, electronic funds transfer, wire transfer, direct deposit, or a cash, draft, or cheque deposit as ways to bring it in (TD’s savings offer page).
Which of the three accounts should I pick?
ePremium for most people: a flat 0.45% on balances of $10,000 or more, no extra conditions (TD’s ePremium Savings Account page). Growth if you already run an eligible TD chequing account and can hit the Boosted rate conditions (TD’s Growth Savings Account page). Every Day only if monthly access matters more than interest — it pays 0.010% (TD’s About Our Interest Calculations (PDF)).
The Club’s take
Who wins: Anyone with $10,000 or more idle at another bank and no TD savings account as of June 3, 2026 — $200 for a four-month park is a 6.08% effective annualized return on the bonus alone, and the $250,000 tier’s $2,500 at 1.00% is still a 3.04% annualized bonus before interest.
Who should skip: Anyone who held a TD savings account on June 3, 2026 — you are excluded. Anyone who might need the money mid-hold. And anyone parking just under a tier top: $24,999.99 earns the same $200 as $10,000, at less than half the percentage.
The catch: The cash is slow. Your money is committed for about 120 days, and TD then has up to 12 weeks after you meet the conditions to pay — open on the last day and the bonus may not land until about May 2027. The interest during the park will not save you either: 0.45% at best on ePremium, 0.010% on Every Day. This offer is the bonus, nothing else.