As of October 3, 2026. One thing to flag: CIBC’s headline offer page is current, but its detailed offer T&Cs (the document carrying the 5-year exclusion, the 1-year direct-deposit and pre-authorized-debit continuation rule, and the payout date) sit behind footnote dialogs not fetchable from cibc.com today — those CIBC fine-print claims are carried over from the offer terms and flagged as such in the text, not independently re-confirmed.
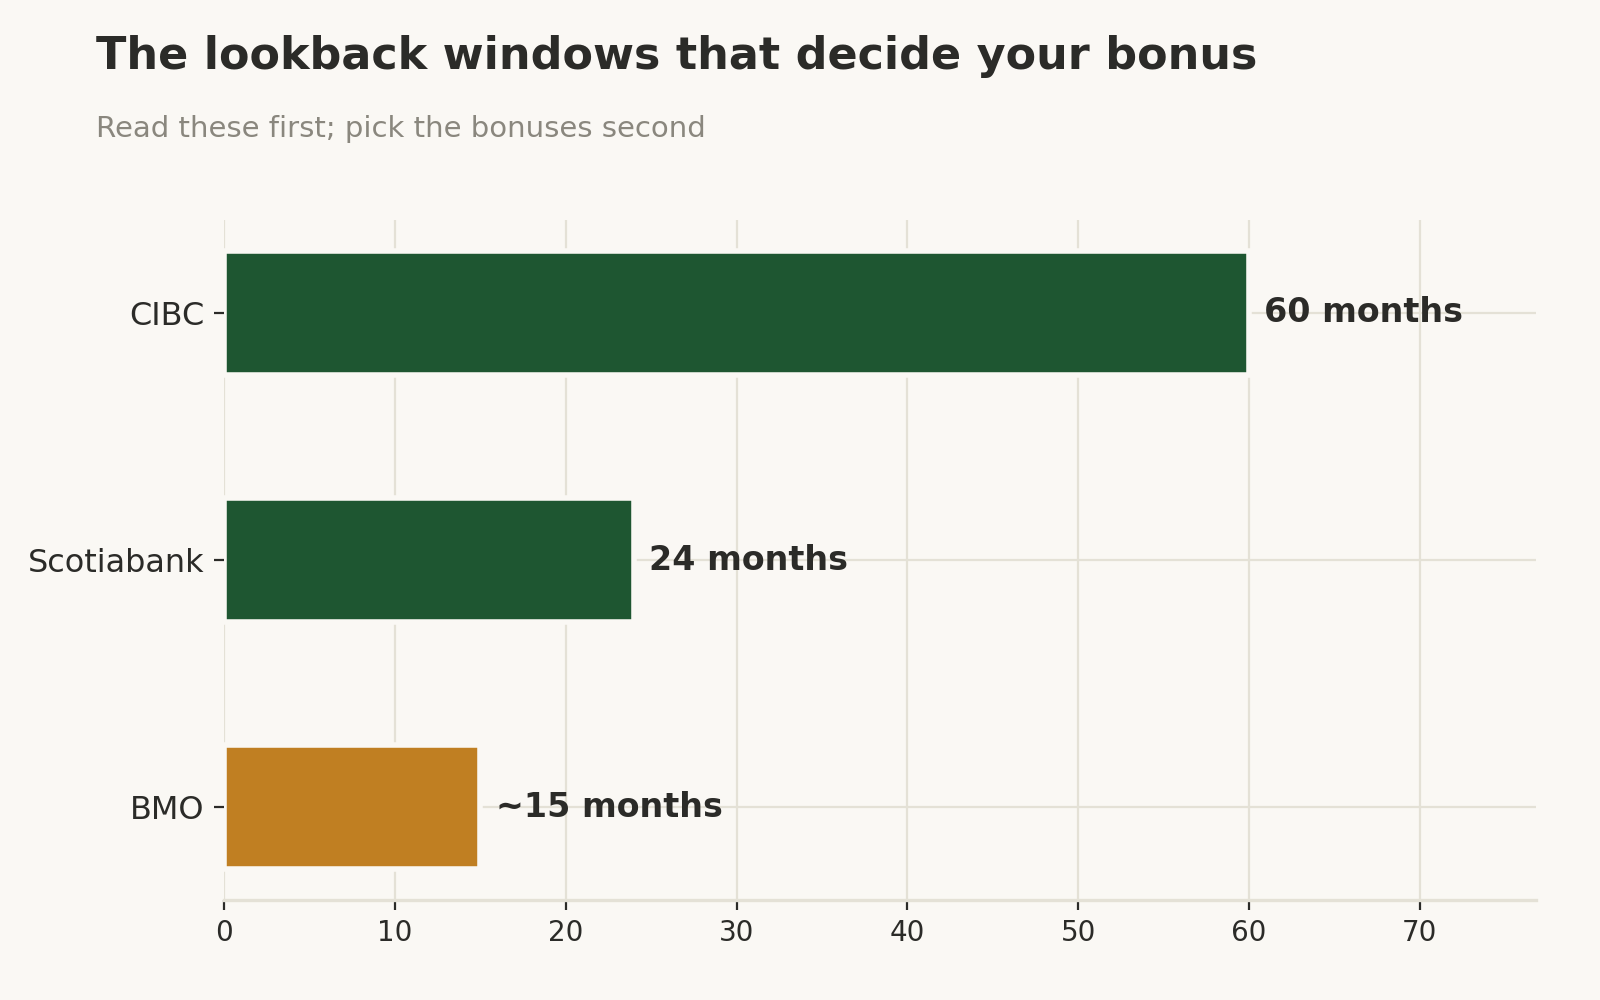
The verdict: Bank account churning in Canada works — but the “who counts as a new customer” fine print decides your actual haul, not the headline bonus. Scotiabank locks you out for 2 years after holding chequing, CIBC for 5 (per its offer T&Cs; not re-confirmable on cibc.com today), and BMO names an exact ineligible date range that catches anyone who closed an account in the last ~15 months. Read the lookbacks first; pick the bonuses second.
Who this is for: Canadians with a steady payroll direct deposit who can route it through 3–4 banks in a year and wait months for payouts. Most bonuses don’t land until 8–10 months after you open the account — payouts are measured from open dates, not from when you finish the requirements.
Who this is NOT for: Anyone who can’t move a direct deposit (irregular income, paper-cheque employers), or anyone who recently held these accounts — the exclusion windows below will disqualify you. Check your history before you apply.
Your move: Match your account history against each bank’s lookback in the table below, then start with the offer expiring soonest — Scotiabank ends October 29, 2026. Track every live bonus on our bank bonus tracker, updated weekly.
Contents
- The exclusion windows — read this first
- Scotiabank: up to $1,000, ends Oct 29, 2026
- BMO: up to 135,000 Blue Points (plus a parallel $900 cash track), ends Nov 2, 2026
- CIBC: up to $850, no expiry stated
- The direct-deposit chains that break bonuses
- Payout timelines and clawbacks
- The 3–4 bonus sequencing playbook
The exclusion windows — read this first
This is where churners lose money. Every bank defines “new customer” as a lookback over your account history, and the windows are all different:
| Bank | Lookback | What disqualifies you |
|---|---|---|
| Scotiabank ($700 piece) | 2 years | Currently hold, or held in the last 2 years, any Scotiabank chequing account (Scotiabank’s offer terms) |
| Scotiabank ($200 piece) | 6 months before offer period | Held a Money Master Account in the 6 months before the offer period (Scotiabank’s offer terms) |
| Scotiabank ($100 piece) | 2 years | Currently or previously a primary cardholder of a Scotiabank personal credit card in the past 2 years (Scotiabank’s offer terms) |
| BMO (Blue Rewards) | Named date range: Aug 7, 2025 – Nov 2, 2026 | Currently hold, or closed in that window, a BMO CAD/USD Primary Chequing, Interest Chequing, Premium Rate Savings, Smart Saver, Savings Builder, or Savings Amplifier account (BMO’s Blue Rewards terms (PDF)) |
| CIBC ($500/$100 pieces) | 5 years (per CIBC’s offer T&Cs — not re-confirmable on cibc.com today) | Holder (or joint holder) of a CIBC chequing account at any time in the past 5 years; for the $100 piece, no CIBC credit card as primary cardholder in the 5 years before opening (CIBC’s offer page) |
BMO’s approach is the sharpest: it doesn’t use a rolling “last 12 months” — it names the exact ineligible window in the terms, and that window moves with each seasonal offer (BMO’s Blue Rewards terms (PDF)). Note that BMO’s prior cash cycle (up to $900) ended August 6, 2026 and used a different window (May 21, 2025–August 6, 2026) (BMO’s prior-cycle terms (PDF)). For the current Aug 7–Nov 2, 2026 cycle, BMO runs two parallel tracks: the Blue Rewards points version below and a cash track paying up to $900 on Performance/Premium plans (plus a Walmart+ membership for up to 12 months), confirmed live on BMO’s cash offer page today (BMO’s offer page).
Joint accounts are a trap across all three: if any holder on a joint account is excluded, nobody on the account qualifies. BMO states it explicitly — if one accountholder is an existing customer or closed an account in the window, none of the accountholders are eligible (BMO’s Blue Rewards terms (PDF)). CIBC requires all accountholders to be eligible (per its offer T&Cs; not re-confirmable on cibc.com today). Scotiabank caps each bonus at one per client and pays the savings/credit pieces only to the primary holder (Scotiabank’s offer terms).
Bank employees are excluded everywhere: BMO excludes Bank of Montreal employees and anyone domiciled with them (BMO’s Blue Rewards terms (PDF)), CIBC excludes current and retired employees (per its offer T&Cs; not re-confirmable on cibc.com today), and Scotiabank excludes employees of Scotiabank and its subsidiaries (Scotiabank’s offer terms).
Scotiabank: up to $1,000, ends Oct 29, 2026
The biggest number on the board — and the slowest payout. The Cash Bonus Bundle runs July 3, 2026 to October 29, 2026 (Scotiabank’s offer terms).
$700 — the chequing piece. Open a new Preferred Package or Ultimate Package chequing account during the offer period. Within 60 days of opening, set up and receive at least one eligible automated recurring direct deposit — payroll or pension — that recurs monthly for a minimum of six consecutive months (Scotiabank’s offer terms). Within 60 days of opening, also complete one of: a recurring pre-authorized transaction of at least $50 that recurs monthly for six consecutive months; one online bill payment of at least $50; or one Visa Debit purchase (online purchases and in-store purchases made outside Canada only) (Scotiabank’s offer terms).
The catch that breaks churners: fund transfers to other Scotiabank accounts (credit card, savings), to accounts at other financial institutions, or to payment processing firms do not count (Scotiabank’s offer terms). Moving your own money between accounts is not a direct deposit. And a single missed month in the six-month chain fails the “consecutive” test.
$200 — the savings bundle. Meet all $700 conditions, then within 60 days of opening the chequing account, open a new Money Master Savings Account and enroll it in a Smart Savings Tool (Pay Yourself First or Savings Finder), staying enrolled for 90 consecutive days (Scotiabank’s offer terms). Separately excluded if you held a Money Master in the 6 months before the offer period (Scotiabank’s offer terms).
$100 — the credit card bundle. Meet all $700 conditions, apply and be approved for an eligible Scotiabank card as primary cardholder within 60 days of opening the chequing account, then make a qualifying purchase within 60 days of the card opening (Scotiabank’s offer terms). Excluded if you were a primary cardholder of any Scotiabank personal credit card in the past 2 years (Scotiabank’s offer terms).
Limit: one $700, one $200, and one $100 per client, for a total of up to $1,000 — regardless of how many accounts you open (Scotiabank’s offer terms).
BMO: up to 135,000 Blue Points (plus a parallel $900 cash track), ends Nov 2, 2026
BMO’s offer window runs August 7, 2026 to November 2, 2026 (BMO’s Blue Rewards terms (PDF)). Three stackable pieces make up the Blue Rewards track:
105,000 points — the chequing piece. Open a new CAD Primary Chequing Account with the Blue Rewards Bank Plan by November 2, 2026. Then: set up one recurring direct deposit of $500 or more from your employer, government, or pension, with the first deposit landing by December 31, 2026; complete one eligible transaction by December 31, 2026 — either two bill payments of $50+ to two different payees through BMO’s online/mobile banking, or two PADs of $50+ from two different payees; and provide a valid email address (BMO’s Blue Rewards terms (PDF)). Exclusions: a transfer from the chequing account to pay a BMO credit card or line of credit doesn’t count as an eligible transaction, and a returned/NSF PAD doesn’t count (BMO’s Blue Rewards terms (PDF)).
22,500 points — the savings piece. Open a Savings Amplifier Account by November 2, 2026, deposit a total of $10,000 or more within the first 30 calendar days, then maintain a daily closing balance of $10,000 or more at all times for an additional 180 calendar days (BMO’s Blue Rewards terms (PDF)). If the daily closing balance dips below $10,000 during the 180-day hold, you lose this piece (BMO’s Blue Rewards terms (PDF)).
7,500 points — the My Financial Progress piece. Qualify for the chequing bonus, sign in to My Financial Progress, create one goal and apply one strategy by December 31, 2026 (BMO’s Blue Rewards terms (PDF)).
Cap: one of each per customer — max 135,000 points regardless of the number of accountholders (BMO’s Blue Rewards terms (PDF)). Students, medical/dental students, recent graduates, kids/teens, and Canadian Defence Community banking plans don’t qualify (BMO’s Blue Rewards terms (PDF)).
The clawback is the long tail: the chequing account must stay open in the Blue Rewards Bank Plan until November 2, 2027, and the savings account must stay open until November 2, 2027 — if you close early or switch plans after points are awarded, BMO reserves the right to claw back the points (BMO’s Blue Rewards terms (PDF)). That’s a full year of keeping the account (and its monthly fees) after the offer ends.
Separately, BMO runs a parallel cash track for the same window — up to $900 cash ($700 chequing + $150 savings + $50 My Financial Progress, on Performance or Premium plans) plus a Walmart+ membership for up to 12 months — confirmed live on BMO’s cash offer page today (BMO’s offer page). Pick one track: you can’t double-dip both for the same accounts.
CIBC: up to $850, no expiry stated
CIBC’s Smart Account offer is the most open-ended — the live offer page states no end date (CIBC’s offer page). Three pieces:
$500 — the Smart Account piece. Open your first CIBC Smart Account, then within 2 months set up at least one recurring direct deposit of $500 or more per month from your employer, government, or pension (CIBC’s offer page). CIBC’s offer terms add a sting to the tail: the required direct deposit and pre-authorized debits must recur weekly, biweekly, monthly, or twice monthly and remain in effect for at least 1 year starting the month after the account was opened (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today).
$100 — the card approval piece. Apply and get approved for any eligible CIBC credit card within one month of opening the Smart Account (CIBC’s offer page).
$250 — the Dividend Visa Infinite piece. Earn 10% cash back up to $200 on net purchases up to $2,000, plus a $50 cash back bonus when you set up your first pre-authorized payment (CIBC’s offer page).
The cost of the account while you wait: the Smart Account charges $16.95 per month (for up to 3 accounts), or $0 with a monthly fee rebate when you keep an end-of-day balance of $4,000 each day of the month in one Smart Account (CIBC’s offer page). Note this sits alongside the 1-year continuation rule above — the cheapest way through the waiting year is usually the $4,000 balance, not paying the fee.
CIBC’s exclusion is the longest in the market (per its offer T&Cs; not re-confirmable on cibc.com today): no holder or joint holder of a CIBC chequing account at any time in the past 5 years, and for the $100 card piece, no primary cardholder of any CIBC credit card in the 5 years before opening. This offer cannot be combined with any other CIBC chequing account offer, rebate, or reward (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today). You must be a Canadian resident age 25 or older (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today).
The direct-deposit chains that break bonuses
Every bank says “direct deposit” and means something specific. The pattern across all three live offers:
- Source matters. Scotia requires payroll or pension — recurring and automated (Scotiabank’s offer terms). BMO requires employer, government, or pension (BMO’s Blue Rewards terms (PDF)). CIBC requires employer, government, or pension (CIBC’s offer page). An Interac e-Transfer from your own other account is not a direct deposit at any of them.
- Continuity matters. Scotia’s chain is the strictest: the deposit must recur monthly for six consecutive months, and the $50+ pre-authorized transaction must also recur monthly for six consecutive months (Scotiabank’s offer terms). One missed month breaks the chain. CIBC requires its DD and PADs to remain in effect for at least a year (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today).
- Timing matters. Scotia: everything set up within 60 days of opening (Scotiabank’s offer terms). BMO: first DD and eligible transactions by December 31, 2026 (BMO’s Blue Rewards terms (PDF)). CIBC: DD set up within 2 months (CIBC’s offer page).
- The Visa Debit quirk (Scotia only). If you use the Visa Debit purchase as your qualifying activity, only online debit purchases and in-store purchases made outside of Canada count — a regular in-store tap in Toronto does not (Scotiabank’s offer terms). The single online bill payment is the simpler path.
Payout timelines and clawbacks
Bonuses are slow money. Plan for “bonuses in flight,” not cash in hand:
| Bank | Payout | Keep-open / good-standing rule |
|---|---|---|
| Scotiabank | $700 ~9 months from account open; $200 ~10 months from savings open; $100 ~10 months from card open (Scotiabank’s offer terms) | All accounts must be open and in good standing until payout — no overdraft beyond the authorized limit, no 3 straight months of overdraft (Scotiabank’s offer terms) |
| BMO (Blue Rewards) | Points applied to your Blue Rewards member number by June 30, 2027 (BMO’s Blue Rewards terms (PDF)) | Chequing must stay open in the Blue Rewards Bank Plan until Nov 2, 2027; savings until Nov 2, 2027 — clawback of awarded points if you close or switch plans early (BMO’s Blue Rewards terms (PDF)) |
| CIBC | Check the current offer T&Cs for the payout date — the headline page doesn’t state it | The required DD/PADs must remain in effect for 1 year from the month after opening (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today) |
Two honest warnings. First, BMO’s prior cash cycle shows how sharp the clawback can be: it reserved the right to debit the accounts for the full bonus value — or send an invoice for any amount outstanding — if you closed before August 6, 2027 (BMO’s prior-cycle terms (PDF)). Treat every offer’s keep-open date as a hard commitment. Second, all three banks can change, shorten, extend, or withdraw their offers at any time without notice — Scotia and BMO both say so in their terms (Scotiabank’s offer terms) (BMO’s Blue Rewards terms (PDF)). Open the offer that’s live today; don’t plan around next quarter’s.
The 3–4 bonus sequencing playbook
Here’s how the rules above turn into a year. This assumes you’re a first-timer at all three banks — every lookback is clean. If any lookback fails, that bank drops out of the sequence until its window clears.
Step 1 — Audit your history (do this today). For each bank, answer: have I held the listed account types inside the lookback window? BMO’s is a named range (Aug 7, 2025–Nov 2, 2026) — pull your statements and check for any BMO chequing or savings account opened or closed inside it (BMO’s Blue Rewards terms (PDF)). Scotia’s is a rolling 2 years for chequing (Scotiabank’s offer terms). CIBC’s is 5 years (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today). One “yes” disqualifies that bank’s main piece.
Step 2 — Scotiabank first (expires Oct 29, 2026). It’s the biggest number and the earliest deadline, and its six-month DD chain starts the longest clock (Scotiabank’s offer terms). Open the Preferred or Ultimate Package, route your payroll DD within 60 days, add the Money Master bundle if you want the extra $200 (check you didn’t hold one in the last 6 months), and the card bundle if you haven’t been a Scotia primary cardholder in 2 years. Use the single online bill payment as your qualifying activity — it’s the simplest of the three options.
Step 3 — BMO second (expires Nov 2, 2026). The window overlaps Scotia’s, which is fine: your payroll can be split into recurring DDs to more than one bank. If you’re chasing the Blue Rewards track, BMO only needs a $500+ recurring DD with the first deposit by December 31, 2026, plus two $50 bill payments or PADs by the same date (BMO’s Blue Rewards terms (PDF)). If you’re chasing the 22,500-point savings piece, the $10,000 must land within 30 days of opening, and the daily closing balance then has to stay at $10,000 or more for an additional 180 days after that deposit window — roughly seven months all-in, so only commit money you won’t need (BMO’s Blue Rewards terms (PDF)). Prefer cash over points? BMO’s parallel cash track pays up to $900 ($700 chequing + $150 savings + $50 My Financial Progress) on Performance/Premium plans for the same window (BMO’s offer page) — pick one track, not both.
Step 4 — CIBC third (no stated expiry). With no deadline, it goes last. The $500 piece needs the DD running within 2 months (CIBC’s offer page) plus one qualifying action completed within a single calendar month, no later than 60 days after opening — one of: two recurring PADs, two online bill payments of at least $50, or five Visa Debit purchases (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today). Budget for the 1-year continuation rule — keep the DD and PADs live for a full year, and either keep a $4,000 daily balance to waive the $16.95 monthly fee or accept the fee as the cost of the bonus (CIBC’s offer page).
Step 5 — Calendar the payouts and the keep-open dates. Scotia pays ~9–10 months out; BMO’s points land by June 30, 2027 with a keep-open date of November 2, 2027 (BMO’s Blue Rewards terms (PDF)). Set reminders for each payout date and each keep-open date. Closing a week early can cost you the whole bonus.
Step 6 — Re-churn on the lookback schedule, not sooner. You can’t re-churn the same bank until its window clears — until your prior holding or closing falls outside the exclusion in the then-current offer’s terms. Each bank measures that window differently: BMO names an exact range (the current cycle names Aug 7, 2025–Nov 2, 2026), Scotiabank chequing uses a rolling 2 years, and CIBC uses 5 years (per CIBC’s offer T&Cs; not re-confirmable on cibc.com today). The churner’s real constraint is that each bank is a one-shot per window — so the game is rotating across banks, not repeating one.
Three rules that override everything: never open a joint account mixing an eligible and an ineligible holder (BMO kills the whole bonus — BMO’s Blue Rewards terms (PDF)); never close before the keep-open date; never count your own account-to-account transfers as direct deposits (Scotiabank’s offer terms).
The math, honestly: Scotiabank’s $1,000 needs ~9 months of patience and 6 months of DD routing. BMO’s 135,000 Blue Points need a year of account upkeep plus $10,000 parked for about 7 months if you want the full stack. CIBC’s $850 needs a year of DD/PAD continuity. That’s the real price of “free” money — calendar time and parked cash, not effort.