As of October 3, 2026. Three details BMO doesn’t publish are flagged in the text.
- The verdict: At $900, this is one of the largest live chequing-account cash bonuses in Canada — though not the biggest: Scotiabank’s current bundle offer runs up to $1,000. It’s a stack of four separate tasks, and the monthly fee eats into it unless you keep a $4,000 balance to waive it. Do the full stack and the net is strong; cherry-pick only the chequing leg and it’s merely good.
- Who this is for: New-to-BMO customers who can reroute a $500+/month direct deposit, make two $50+ bill payments (or set up two pre-authorized debits), and park $10,000 in a savings account for about 7 months.
- Your move: Open the Performance Plan by November 2, 2026, complete the direct deposit and bill-payment steps by December 31, 2026, and decide whether you’ll pay the $17.95/month fee or hold a $4,000 minimum balance to waive it.
On this page
- The honest net math
- What you have to do: the four legs
- The fee question: pay it or waive it?
- The savings leg: $150 + a 4-month promo rate on $10,000
- Cash vs. “135,000 Blue Rewards points”: same offer, two tracks
- Walmart+: the freebie on top
- The catch list
- Step-by-step: your move
The honest net math
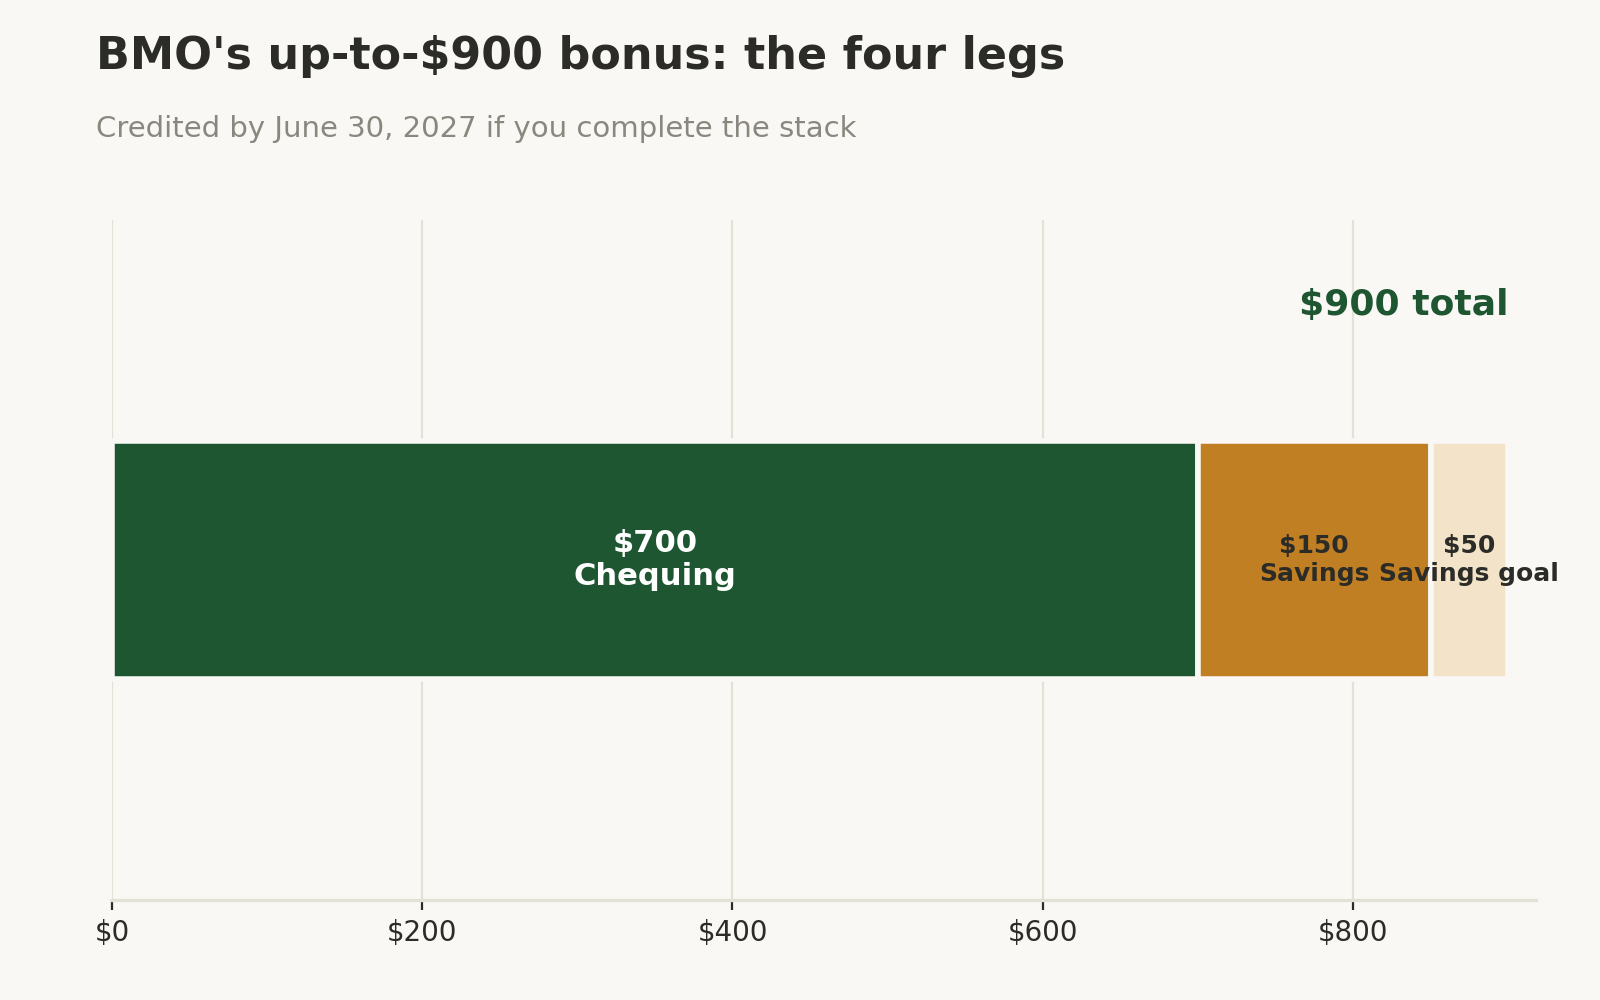
BMO’s offer pays up to $900 cash, credited by June 30, 2027. The current-cycle cash terms break it into three parts:
| Leg | Bonus | Paid to |
|---|---|---|
| Open + fund a Performance or Premium chequing account, set up $500+/mo recurring direct deposit, complete the bill-payment/PAD requirement | $700 | Chequing account |
| Open a Savings Amplifier Account, deposit $10,000+ within 30 days, hold the balance ~7 months | $150 | Savings account |
| Set up a savings goal in My Financial Progress | $50 | Chequing account |
Plus a Walmart+ membership for up to 12 months on top (first month from Walmart, eleven from BMO).
Now the costs. The Performance Plan charges $17.95/month, and the Premium Plan charges $30.95/month. BMO’s published terms confirm the $700/$150/$50 stack on the Performance Plan ($900 total); the terms table leaves the Premium Plan’s bonus cells blank, so Premium’s payout is unconfirmed — either way, there’s no published reason to pay Premium’s higher fee for this offer.
Scenario A — pay the fee: Hold the Performance Plan for roughly 12 months at $17.95 = $215.40 in fees. Net: $900 − $215.40 = $684.60 in cash, plus the Walmart+ membership and roughly $164 of savings interest (at BMO’s confirmed 5.00% promo rate; BMO’s own worked figure is $164.38 on $10,000 over 120 days — see the savings leg).
Scenario B — waive the fee: Keep a $4,000 minimum balance in the chequing account and the $17.95 fee drops to $0. Net: the full $900, at the opportunity cost of $4,000 sitting in chequing.
Why ~12 months of fees? BMO’s current-cycle cash terms require the chequing account to stay open and in an eligible plan until November 2, 2027, with BMO reserving the right to claw the bonus back (by debiting your account or sending an invoice) if you close or switch plans before then. Twelve months of fees is the conservative case.
Either way, this clears the bar comfortably: $684–$900 net cash against a few hours of setup. The “hoops” are real, but so is the payout.
What you have to do: the four legs
1. Open and fund a new Performance or Premium chequing account by November 2, 2026. This offer is for new customers — if you currently hold a BMO chequing or savings account (or closed one between August 7, 2025 and November 2, 2026), you’re out. Provide a valid email address at account opening.
2. Set up a recurring direct deposit of at least $500 — from your employer, the government, or a pension — with the first deposit landing in the account by December 31, 2026.
3. Complete one of these by December 31, 2026:
– Make two bill payments of $50 or more to two different payees through online or mobile banking, or
– Set up two pre-authorized debits of $50 or more from two different payees, with at least one debit appearing from each.
Bill-payment fine print that matters: payments must be done through online or mobile banking, minimum $50 each, and each payment must go to a different payee. A transfer from your chequing account to pay a BMO credit card or a BMO line of credit does not qualify — so don’t use your BMO Mastercard bill as one of the two. The flip side: pre-authorized debits to a BMO mortgage, BMO loan, BMO line of credit, or a BMO investment account do count as qualifying PADs. A PAD that bounces (NSF, stop payment) doesn’t count.
4. The savings and My Financial Progress legs (below).
The fee question: pay it or waive it?
This is the single decision that determines your net. The Performance Plan is $17.95/month, waived with a $4,000 minimum balance. The Premium Plan is $30.95/month, waived with $6,000 — but BMO’s terms confirm the full $900 stack on Performance, so there’s no published reason to pick Premium for this offer.
If you keep the account for roughly a year (open Oct–Nov 2026 through the payout window and beyond), that’s $215.40 in fees against the $900 — still a $684.60 net win. If you can afford to leave $4,000 untouched in chequing, the fee disappears entirely. Either way you come out ahead; the only losing move is paying the fee without finishing the requirements — then no bonus lands to cover it. Collect the $900 and it covers the $215.40 in fees more than four times over; run your own numbers if your fee or timeline differs.
One more detail: to earn the savings and My Financial Progress bonuses, you need the Performance or Premium Plan — the savings and MFP legs both require qualifying for the chequing bonus with one of those two plans.
The savings leg: $150 + a 4-month promo rate on $10,000
The savings leg has the longest hold of anything in this offer:
- Open a new Savings Amplifier Account by November 2, 2026.
- Deposit $10,000 or more within 30 days of opening.
- Maintain a daily closing balance of $10,000 or more at all times for 120 calendar days from the date of deposit — that’s the promotional-rate window — then keep it there for an additional 90 calendar days to earn the $150 cash bonus. Either way: your $10,000 is committed for roughly 7 months from the deposit date.
The rate: BMO’s Savings Amplifier page confirms a promotional rate of 5.00% for up to 120 days when the savings account is opened together with an eligible chequing account. The 5.00% applies on balances up to $1,000,000. BMO’s offer-page footnote estimates $164.38 in total interest on $10,000 over the 120-day window — exactly what the confirmed 5.00% pays ($10,000 × 5.00% × 120/365), so read $164.38 as BMO’s own worked example at a confirmed rate, not a guess.
So the savings leg is worth roughly $164 in interest + $150 cash = ~$314 on $10,000 over ~7 months (interest at the confirmed 5.00% promo rate — BMO’s own worked figure is $164.38 on $10,000 over 120 days). That’s not dead money — but it does mean locking up $10,000 until roughly June 2027. Also note: BMO’s terms say you must qualify for the chequing-leg bonus with the Performance or Premium Plan to earn the savings bonus too. The $150 is paid into the savings account by June 30, 2027 — and your savings account must stay open until November 2, 2027, or you lose the offer (BMO can claw back a paid bonus).
Cash vs. “135,000 Blue Rewards points”: same offer, two tracks
Some sites describe this offer as “135,000 Blue Rewards points.” Here’s what’s going on: BMO runs the same stacked offer on two parallel, separately enrolled tracks for the same August 7 – November 2, 2026 window:
| Track | Chequing leg | Savings leg | My Financial Progress | Total |
|---|---|---|---|---|
| Cash track | $700 | $150 | $50 | $900 |
| Blue Rewards points | 105,000 pts | 22,500 pts | 7,500 pts | 135,000 pts |
The arithmetic implies BMO values 150 points = $1 (135,000 ÷ 150 = $900). The tracks are genuinely separate: the points track requires opening a chequing account with BMO’s Blue Rewards Bank Plan and providing a Blue Rewards Member Number (enrollment via BMO’s Blue Rewards enrollment page), while the cash track uses the Performance/Premium/Practical plans (enrollment via BMO’s cash-bonus enrollment page). In practice you can only earn one: each track requires opening a new account as a non-existing BMO customer, so completing one makes you an existing customer for the other. Cash is the simpler, more transparent choice — take the cash track.
Walmart+: the freebie on top
Open a new chequing account (Practical, Plus, Performance, or Premium) and deposit any amount by November 2, 2026, then sign up for or update your Walmart+ membership on Walmart.ca by December 31, 2026 — selecting Debit Mastercard as the recurring monthly payment option and entering your 16-digit BMO debit card number. You get up to 12 months: the first month from Walmart, then eleven months from BMO.
Heads-up on the mechanics: Walmart+ charges $8.97/month (plus tax) to your chequing account, and BMO reimburses it within 30 days — so it’s genuinely free, but not hands-off. Cancel early and you forfeit the remaining months. Existing BMO customers and employees are excluded. No extra transactions required beyond the account opening and the Walmart+ signup.
The catch list
- New customers only. You can’t currently hold a BMO chequing or savings account — or have closed one between August 7, 2025 and November 2, 2026.
- Keep it open. Your chequing account must stay open in an eligible plan until November 2, 2027, and your savings account must stay open until November 2, 2027. Close or switch early and BMO can claw the bonus back — by debiting your account or sending you an invoice.
- One per customer. One chequing offer, one savings offer, one My Financial Progress offer per customer — no double-dipping with a joint account; the total is capped at $900 regardless of how many holders are on the account.
- Discounted plans are mostly excluded. Students, medical/dental students, recent graduates, and Canadian Defence Community banking plans don’t qualify; the Plus Plan is excluded from the direct-deposit, MFP, and savings offers — though unlike those, it does qualify for the Walmart+ membership. BMO’s FAQ also names specific included programs (Seniors, NewStart, RDSP, Indigenous Banking, Bank at Work) — but that FAQ text appears to be from an older offer cycle, so confirm directly with BMO if you’re on one.
- BMO can change or withdraw the offer at any time without notice.
- The money takes time. Requirements complete by Dec 31, 2026, but the bonus isn’t credited until June 30, 2027 — that’s up to a 6-month wait after you finish the work.
- BMO employees (and those domiciled with them) are excluded.
Step-by-step: your move
- Open a BMO Performance Chequing Account by November 2, 2026, and fund it with a deposit of any amount.
- Reroute a $500+/month direct deposit (pay, government, pension) so the first deposit lands by December 31, 2026.
- Pay two $50+ bills to two different billers via the BMO app/online banking — or set up two $50+ pre-authorized debits from two different payees. (Don’t use a BMO credit card or BMO line of credit bill payment as one of the two.)
- Open a Savings Amplifier Account by November 2, 2026, deposit $10,000+ within 30 days, maintain a $10,000+ daily balance for 120 calendar days, then for an additional 90 calendar days to earn the $150 cash bonus — roughly 7 months total.
- Open My Financial Progress in online/mobile banking, create one savings goal, and apply one strategy to your plan — all by December 31, 2026.
- Sign up for Walmart+ by December 31, 2026 with Debit Mastercard selected.
- Decide on the fee: keep a $4,000 minimum balance to waive the $17.95/month, or accept ~$215 in fees over the year and still net ~$685.
- Leave everything alone until the bonus lands (by June 30, 2027) — and keep both accounts open until November 2, 2027 to avoid a clawback.