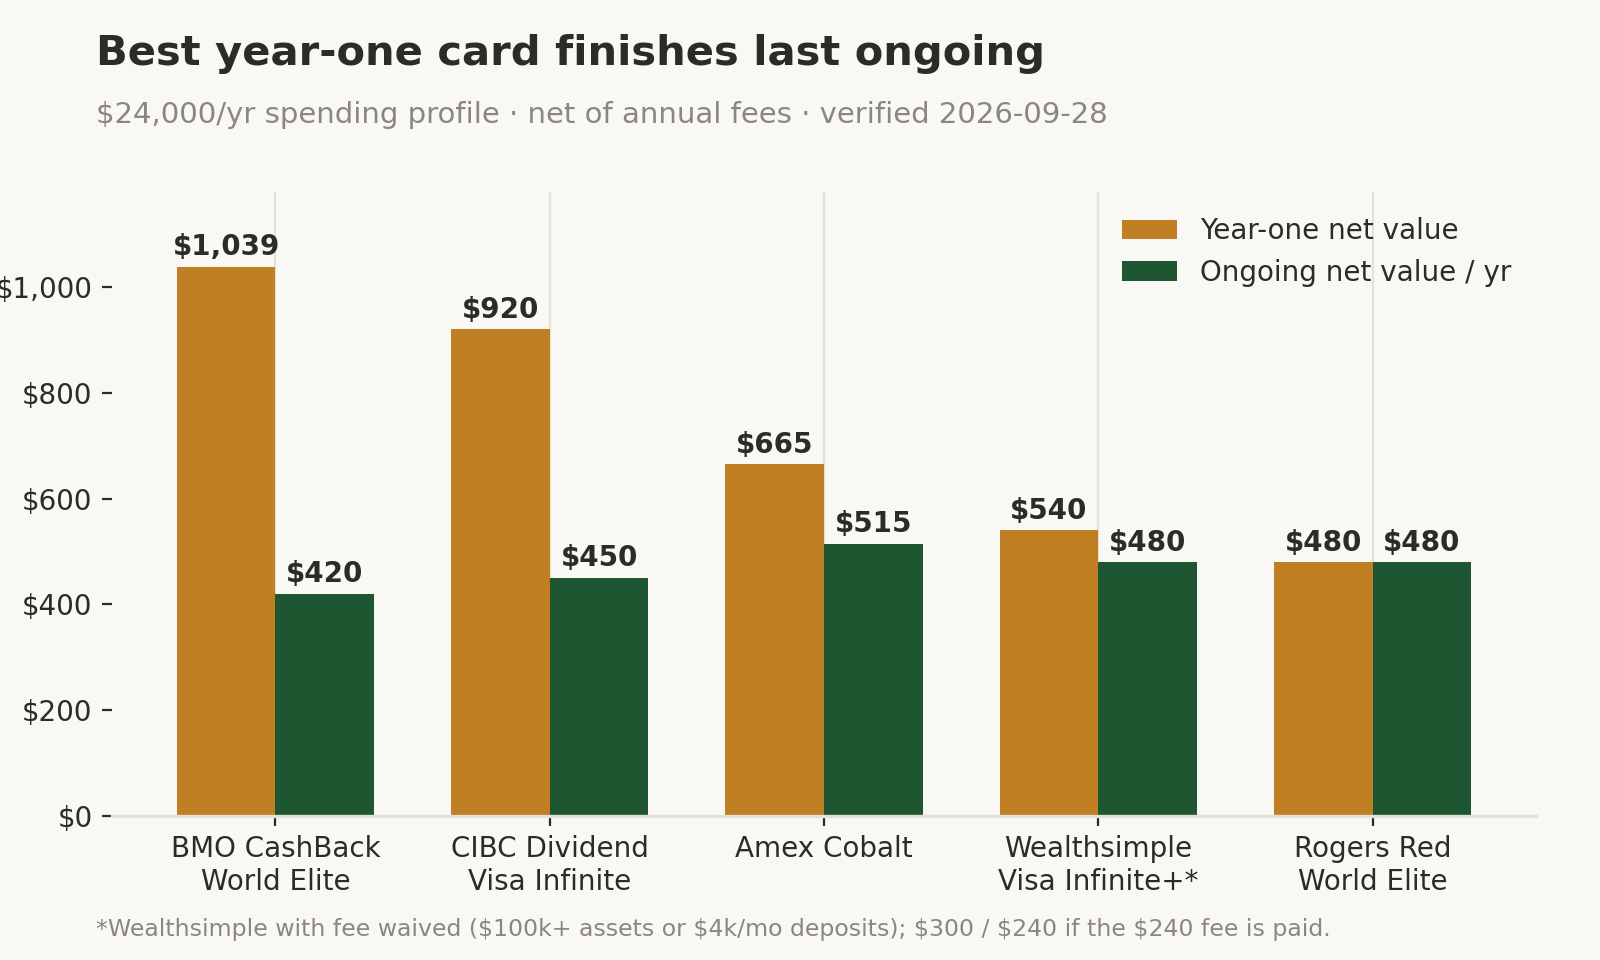
The verdict: On a $24,000/year spending profile, the BMO CashBack World Elite wins year one at ≈$1,039 in net value — but it falls to last place ongoing (≈$420), where the Amex Cobalt's 5x on food leads at ≈$515 net and the no-fee Rogers Red World Elite pays a flat $480.
Who this is for: Canadians picking a cash-back card who want the ranking done by dollars, not vibes.
Your move: Chase BMO's year-one bonus only if you can reliably spend $2,000/month — otherwise take the Cobalt for food-heavy spend, or the Rogers card for a no-fee flat rate.
Title: The Best Cash-Back Credit Cards in Canada (2026), Ranked by the Math
Slug: best-cashback-credit-cards-canada-2026
Sources checked: 2026-09-28. Offer availability compared against today's date per the playbook date rule. Every number below is tied to a live source URL. Where the card issuer is silent on a term, a reputable third-party tracker is cited and labeled as such.
Most "best credit card" lists rank by vibes, sponsored placements, or headline earn rates that collapse the moment you read the fine print. This one ranks by dollars: a defined spending profile, the cards' actual earn structures, and net value after fees — first year and ongoing.
The spending profile (all math flows from this)
Annual spend: $24,000 ($2,000/month), split as:
Groceries: $600/mo ($7,200/yr)
Dining / food delivery: $300/mo ($3,600/yr)
Gas and EV charging: $150/mo ($1,800/yr)
Transit: $80/mo ($960/yr)
Streaming and recurring bills: $120/mo ($1,440/yr)
Everything else: $750/mo ($9,000/yr)
Balances paid in full every month (interest charges would swamp any rewards on all of these cards). For the Rogers card, the math assumes you're a Rogers, Fido, or Shaw customer, since that's where the card's value lives.
None specified — Amex publishes no income requirement for this card (MoneySense)
Up to 15,000 MR points (1,250/month × 12 months at $750/mo spend), no published end date (issuer)
2.5% (not disclosed on issuer pages retrieved; Frugal Flyer)
Rogers Red World Elite
3% USD purchases; 2% everything else with an eligible Rogers, Fido or Shaw service (1.5% without); from Nov 18, 2026: 5% on eligible Rogers purchases (issuer calculator; issuer change notice)
$240/yr ($20/mo; $240 charged annually in QC), waived with $100,000+ in Wealthsimple assets or $4,000+/mo direct deposits (issuer)
$80,000 personal / $150,000 household; Canadian resident, age of majority, active Wealthsimple chequing account (issuer)
Up to 5% back for new clients' first 30 days (issuer); third parties report a $500 cap (first $10,000 in purchases) and a 180-day clawback (milesopedia)
Up to $350 in value: 10% cash back up to $200 (net purchases up to $2,000, first 4 statements) + $50 pre-authorized-payment bonus + $120 first-year fee rebate; no published end date (The Points Standard, reviewed 2026-09-28)
$40 cash back each month you spend ≥$2,000 net in each of the first 12 billing cycles (up to $480) + first-year fee waiver; apply by Nov 30, 2026 (63 days after 2026-09-28 — still available) (issuer terms)
BMO CashBack World Elite — ≈$1,039. Ongoing earn on the profile: groceries 5% on $6,000 ($300) + 1% on the remaining $1,200 ($12) = $312; gas $1,800 × 3% = $54; transit $960 × 4% = $38.40; recurring bills $1,440 × 2% = $28.80; everything else ($3,600 dining + $9,000 general) × 1% = $126. Total ≈ $559, all from the issuer's earn terms (issuer terms). Add the $480 monthly bonus (requires $2,000/month in net purchases — the profile spends exactly $2,000/month, so assume it's achievable, but a leaner month breaks a $40 payment) with the $139 fee waived in year one: $559 + $480 = ≈$1,039 in year-one value. Note the bonus is demanding: miss the $2,000 in any billing cycle and that month's $40 is gone. (issuer terms)
CIBC Dividend Visa Infinite — ≈$920. Ongoing: groceries $7,200 × 4% = $288; gas $1,800 × 4% = $72; transit, dining, recurring ($960 + $3,600 + $1,440) × 2% = $120; everything else $9,000 × 1% = $90. Total $570, all from the issuer's earn page (issuer). Year one adds the advertised up to $350 in offer value ($200 at 10% on the first $2,000 of net purchases over 4 statements, $50 pre-authorized payment bonus, $120 fee rebate): $570 + $350 = $920 (The Points Standard). CIBC notes the offer is digital-exclusive and excludes anyone who opened, transferred or cancelled another Dividend card in the last 12 months (milesopedia).
Amex Cobalt — ≈$857 gross / $665 net. Points on the profile: eats & drinks ($7,200 groceries + $3,600 dining) × 5 = 54,000; streaming ($360) × 3 = 1,080; gas + transit ($2,760) × 2 = 5,520; everything else ($10,080) × 1 = 10,080. Total 70,680 points. At 1¢ per point (the statement-credit redemption rate — 1,000 points = $10, per issuer benefits; MoneySense notes higher value possible via 1:1 airline transfers), that's ≈$707 in year-one ongoing value, minus the $191.88 fee = ≈$515 net. Add the welcome offer of up to 15,000 points (≈$150 at 1¢; new cardmembers only — current or former Cobalt cardholders are excluded) and year-one net ≈ $665. Note: the 5x food category carries a $2,500/month combined spending cap (issuer benefits) — the profile's $900/month is well under it.
Wealthsimple Visa Infinite+ — ≈$540 net (fee waived) / ≈$300 net (fee paid). Flat 2% × $24,000 = $480 (issuer). Minus the $240 annual fee = $240 net if you pay the fee; $480 if you qualify for the waiver ($100k+ assets or $4k/month deposits). Year one adds the welcome boost (up to 5% back for the first 30 days for new clients, confirmed by the issuer); at ~$2,000 of first-month spend that's roughly $100 total (≈$60 above the regular 2%). The boost mechanics — a $500 cap on the first $10,000 and a 180-day clawback — are reported by milesopedia (third-party; Wealthsimple's promo T&Cs weren't retrieved), and The Points Standard notes the card has been invite-limited at times, so treat the $60 as upside rather than guaranteed. The card's real edge is 0% foreign transaction fees — the only card here with no FX fee (issuer).
Rogers Red World Elite — ≈$480. No welcome offer is currently published (milesopedia, September 2026), so year one equals ongoing: 2% × $24,000 = $480 for a Rogers/Fido/Shaw customer, $0 fee (issuer calculator). From November 18, 2026, cardholders also earn 5% on eligible Rogers purchases (e.g., a Rogers/Fido/Shaw postpaid mobile bill), per Rogers Bank's own change notice (issuer change notice). Note: the same notice ends the 1.5x redemption multiplier on November 18, 2026 — after that, all redemptions are a flat 1¢ per point (issuer change notice). If you're not a Rogers/Fido/Shaw customer, the rate drops to 1.5% ($360) and this card falls out of contention.
The ranking: ongoing value (year two and beyond)
Amex Cobalt — ≈$515 net. ≈$707 in points value minus $191.88. Wins for anyone who spends heavily on food: the 5x on groceries and dining is the highest sustained earn rate in this comparison. Caveats: the $191.88 fee is steep (only Wealthsimple's $240 is higher), Amex acceptance is narrower than Visa/Mastercard, and the 2.5% FX fee (Frugal Flyer) makes it a poor travel-spend card.
Rogers Red World Elite — $480. A flat 2% with no fee and no category tracking is hard to beat for simplicity — if you're a Rogers, Fido, or Shaw customer and spend under the $61,000/year annual cap on the accelerated rate (issuer change notice). Post-November 18, the 5% rate on eligible Rogers purchases adds a meaningful boost for telecom bills (issuer change notice). Non-Rogers customers: $360, which changes the ranking below.
Wealthsimple Visa Infinite+ — $480 net (waived) / $240 net (paid). Same $480 gross as Rogers, but the value is fee-dependent: at the full $240 fee it drops to fourth place; with the waiver (realistic for its target audience of $100k+ Wealthsimple clients) it ties Rogers — with 0% FX fees as the tiebreaker for anyone who spends in foreign currency (issuer).
CIBC Dividend Visa Infinite — $450 net. $570 gross minus the $120 fee (issuer). The 4% on groceries and gas makes it the strongest pick for households with high grocery spend that shops outside BMO's $500/month grocery cap.
BMO CashBack World Elite — ≈$420 net. ≈$559 gross minus the $139 fee (issuer terms). The best year-one card collapses to last place ongoing — the $139 fee plus capped categories mean the welcome bonus was doing all the work. Worth keeping past year one only if your grocery spend fits neatly under the $500/month cap and you value the included roadside assistance (valued at $75/year, issuer terms).
The Rogers devaluation: what actually changed
The ranking above uses the post-November 18, 2026 Rogers earn structure, because that's the card you'll hold for most of any year. Per Rogers Bank's own change notice (issuer change notice): the 1.5x redemption bonus on eligible Rogers purchases ends November 18, 2026 (no grandfathering — all redemptions become a flat 1¢ per point), and earn on eligible Rogers purchases rises to 5% from the same date, subject to the card's annual limits. Trip cancellation, trip interruption, and trip delay insurance are also removed November 18, 2026, and the 5 annual Roam Like Home days become a $75 roaming credit on January 12, 2027. Until November 18, the card still earns 2% (Rogers/Fido/Shaw customers) / 1.5% on CAD purchases and 3% on USD purchases, with a 2.5% foreign transaction fee (issuer calculator). Net effect for a pure cash-back user: the card stays a strong 2% no-fee flat card, and gets better if you pay a Rogers-family mobile bill with it.
Which card for which reader
Maximum ongoing cash back, food-heavy spend: Amex Cobalt — but only if you can live with the $191.88 fee and Amex acceptance.
Simplest no-fee flat rate: Rogers Red World Elite — but only for Rogers/Fido/Shaw customers; without the 2% tier, Wealthsimple (waived) or CIBC win.
Fee-waived flat 2% + no FX fees: Wealthsimple Visa Infinite+ — the ecosystem card; skip it if you won't hit the waiver, because the $240 fee halves its value.
Highest grocery rate: CIBC Dividend Visa Infinite — 4% on groceries and gas, lowest income bar in this comparison ($60,000 personal vs. $80,000 elsewhere).
Best year-one haul: BMO CashBack World Elite — $480 in monthly bonuses plus a waived fee, if you can reliably spend $2,000/month; plan to reassess at renewal.
What this comparison assumes (and where it breaks)
Amex points valued at 1¢ each — the statement-credit rate (1,000 points = $10, issuer benefits); MoneySense notes ~1.5¢ average via Fixed Points Travel, up to 2¢ via airline transfers. If you transfer to Aeroplan and redeem well, the Cobalt's lead grows; if you redeem at Amazon's Shop with Points rates, it shrinks.
Rogers customer assumption — the 2% tier requires an eligible Rogers, Fido or Shaw service in good standing (issuer calculator).
BMO's $40/month bonus requires $2,000 in net purchases every billing cycle (issuer terms); the profile spends exactly that, so one thin month costs $40.
Wealthsimple's boost exists per the issuer (issuer); its cap ($500 on the first $10,000) and 180-day clawback are third-party reported (milesopedia), and availability has been invite-limited at times per The Points Standard — the $60 year-one boost value is upside, not guaranteed.
Foreign spending is excluded from the profile; if you spend heavily in foreign currency, Wealthsimple's 0% FX fee (issuer) changes the math materially, and the Rogers card's 3%-on-USD-minus-2.5%-FX nets only ~0.5%.
Refresh notes
This article needs monthly refresh. Card offers change constantly:
Welcome offers: BMO's offer requires applications by Nov 30, 2026 — after that date, the year-one ranking must be re-run. The CIBC and Amex offers have no published expiry dates as of 2026-09-28; re-check the issuer pages monthly. Watch item: milesopedia currently shows a higher CIBC variant (up to $400 value / $250 bonus cap) than The Points Standard's up-to-$350 version used in the math above — confirm which is live before the next refresh.
Rogers structure: the November 18, 2026 changes (1.5x redemption end, 5% Rogers-purchase earn start, insurance removal) take effect mid-refresh-cycle — re-verify the earn structure after that date.
Wealthsimple: the welcome boost's full T&Cs live on Wealthsimple's promo terms (linked from the card page); re-confirm cap, clawback and end date monthly.
Resolved in verification 2026-09-28: Amex 5x $2,500/mo cap (now first-party), Amex welcome offer (now first-party), Rogers $0 fee and $80k/$150k income (now first-party), Rogers $61,000 annual cap (now first-party), BMO Nov 30 deadline + $480 bonus mechanics (first-party), CIBC earn rates/fee/income (first-party), Wealthsimple fee/waiver/eligibility/0% FX (first-party). FX fees for Amex, CIBC and BMO (all 2.5%) remain third-party reported — the issuers don't disclose them on the pages retrieved.
Re-run the profile math whenever any earn rate, fee, or cap changes; keep the $24,000 profile definition stable for comparability between refreshes.